
Photo 1 of 5
EUR 295K
Converting...
Ernst-Thälmann-Str. 18, Dassow
HouseGermanyErnst-Thälmann-Str. 18, 23942, Dassow Visit 4TREE Capital Real Estate's portal (opens in a new tab)Mirko Zill 040 53 799 68414

13 listings
Visit 4TREE Capital Real Estate's portal (opens in a new tab)Mirko Zill 040 53 799 68414 Country guide · 24 minGermany Investor GuideInvesting in Europe's Largest Economy, Berlin, Munich, Frankfurt, and the German Real Estate MarketEU MemberEUR StableForeign-FriendlyRead the guide
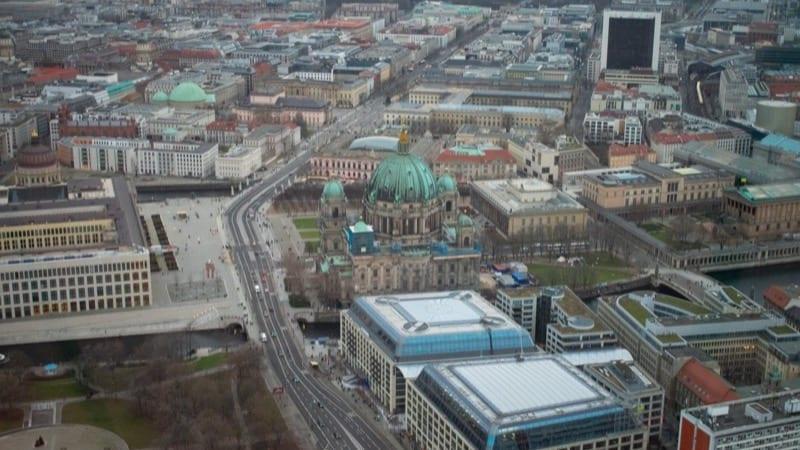 City guide · 8 minBerlinBerlin is Europe's capital of creativity and one of its most resilient property markets. Germany's largest city by population (~3.8 million) and the political heart of the EU's largest economy, Berlin has transformed over three decades from a divided post-Cold War curiosity into a global hub for startups, art, music and progressive urbanism. The property market is anchored by strong tenant protections, a chronic supply shortfall, and rising rents that consistently outpace national averages. Average prices in central districts run EUR 5,500-9,500 per square metre, with rental yields of 3.2-4.5% gross. The 2025 federal coalition's housing legislation extending Mietpreisbremse rent controls through 2029 keeps yield compression real, but the structural undersupply (Berlin needs ~20,000 new units per year and consistently builds half that) keeps capital values trending up. For international investors, Berlin offers EU-grade legal certainty, deep liquidity, English-speaking professional services, and a market that proved its defensive credentials during the 2022-24 rate cycle. The catch: yields are thin and tenant law tilts heavily toward the tenant. Best suited to long-term capital preservation buyers rather than yield hunters.
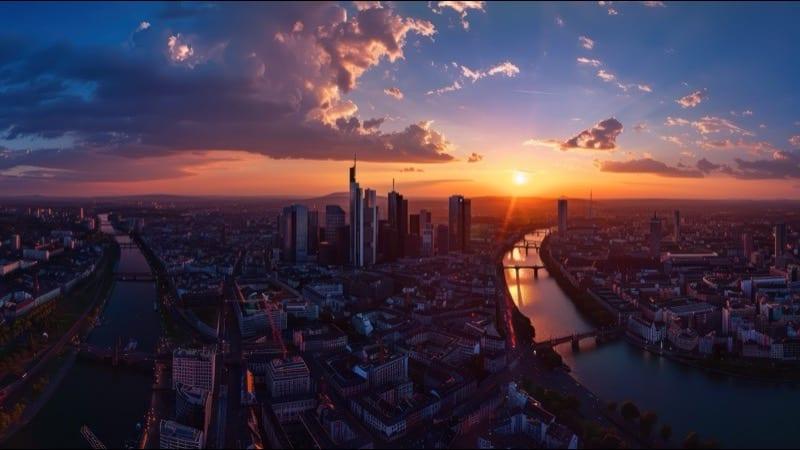 City guide · 8 minFrankfurtFrankfurt is continental Europe's financial capital and home to the European Central Bank, Deutsche Bank, Commerzbank, and the post-Brexit beneficiaries of London's banking exodus (JPMorgan, Goldman Sachs, Morgan Stanley have all expanded EU operations here). Property prices reflect this concentrated wealth: city-centre residential runs EUR 6,500-12,500 per square metre with rental yields of 3.0-3.8% gross. Frankfurt punches well above its 770,000-resident population thanks to a daily commuter influx of more than 350,000 financial professionals. This drives premium rental demand in city-centre apartments and prime suburban houses in Westend, Sachsenhausen, and Nordend. The city's skyline, the only true skyscraper cluster in continental Europe, gives it an Americanised feel that institutional capital finds reassuring. For international buyers, Frankfurt offers ECB-grade liquidity, an English-speaking professional environment, deep transport links via Frankfurt Hauptbahnhof and FRA airport (Europe's 3rd-busiest), and consistent demand from financial services tenants who pay above-market rents. Risk: high concentration in financial sector cycles.
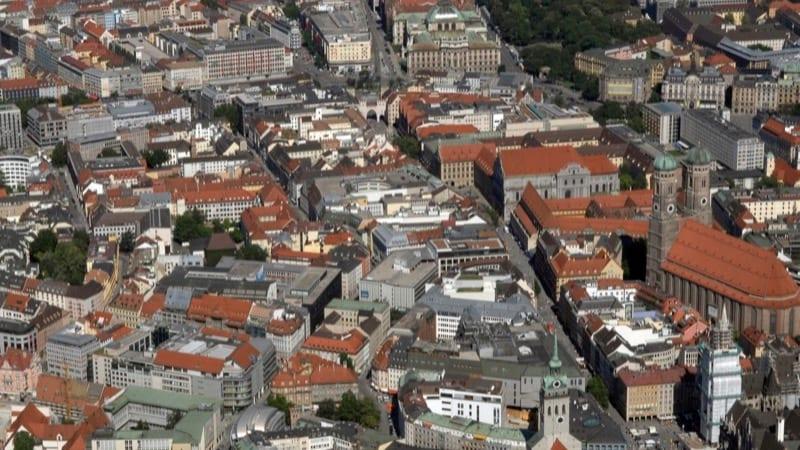 City guide · 8 minMunichMunich is Germany's most expensive city and its strongest property market on a fundamentals basis. The Bavarian capital combines blue-chip corporate employers (BMW, Siemens, Allianz, MunichRe), Germany's lowest unemployment, and a constrained land supply hemmed in by Alpine geography. The result is a market where average residential prices have nearly tripled since 2010 and gross yields have compressed below 3% in central districts. Prices in core neighborhoods like Altstadt-Lehel, Maxvorstadt and Schwabing range from EUR 9,500 to EUR 18,000 per square metre. Outer ring districts offer EUR 6,500-9,000 per sqm. Rental yields run 2.8-3.5% gross, the lowest in Germany, but with the strongest rental demand and the most defensive tenant base (professionals on Bavarian salaries are roughly 20% above the German average). For international buyers, Munich is a pure capital-preservation play with currency-hedged Eurozone safety and an A+ tenant pool. Yield-focused investors should look elsewhere; long-term wealth-protection buyers consistently rank Munich as a top-3 European destination alongside Zurich and Geneva.
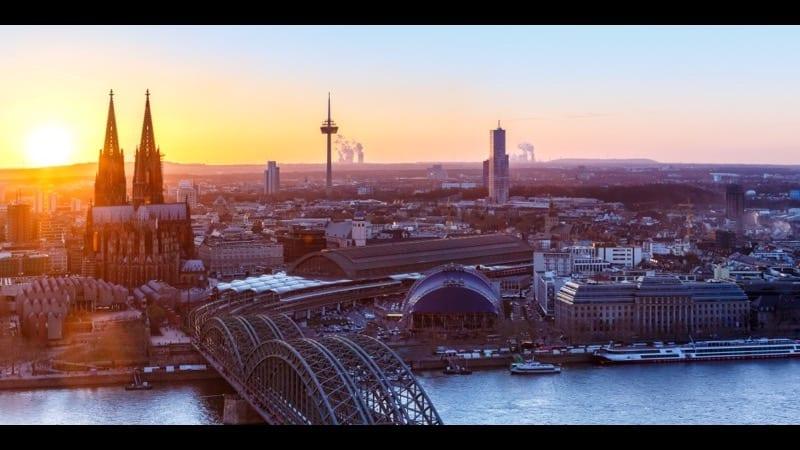 City guide · 7 minCologneNorth Rhine-Westphalia's largest city and the cultural and media heart of the Rhineland, Cologne offers international investors a deep, liquid residential market within Germany's most populous metropolitan region, Rhine-Ruhr. The city's economy blends media and broadcasting, insurance, logistics and a major trade-fair complex, supporting steady, broad-based rental demand. Prime values concentrate in leafy Lindenthal and the central Innenstadt and Neustadt, where existing apartments trade around €4,200–€4,330 per square metre and new-build stock reaches roughly €7,310 per square metre; mid-market gentrifiers Ehrenfeld and Nippes, among the German neighbourhoods forecast to see the strongest 2026 price growth, combine accessibility with appreciation potential. Cologne's market-active vacancy rate sits between 0.5% and 1.2%, with near-zero effective vacancy in high-demand quarters such as Ehrenfeld and Neustadt. Rents remain anchored by the official Mietspiegel, keeping gross yields modest at roughly 3.0% citywide (a 2.3–4.2% spread driven primarily by location). With prices up about 5% year-on-year as the market recovers from the 2022–2023 correction, mortgage rates stabilising, and a base-case five-year cumulative growth estimate near 20%, Cologne enters 2026 as a steady, income-and-growth core market for buyers prioritising liquidity and tenant depth.
 Market insight · 10 minThe Rent Regulation Wave: What Section 21, Ireland's National Cap and Spain's Vanishing Listings Mean for YieldsEngland ended no-fault eviction, Ireland capped rents nationally and Spain's rental supply fell up to 51%. Rent regulation is now a pricing input, not a political footnote.
 Market insight · 10 minEuropean Residential Real Estate in 2026: Record Institutional Flows, Rate Reversals, and Why the Supply Deficit Trumps Monetary PolicyRecord €53B institutional flows into European residential in 2025 reflect a structural thesis, not a rate-cut trade. Spain at +12.8%, Germany at a decade construction low, and 2.25M EU housing deficit make the supply story far stronger than the rate narrative.