City guides
City guides (402)
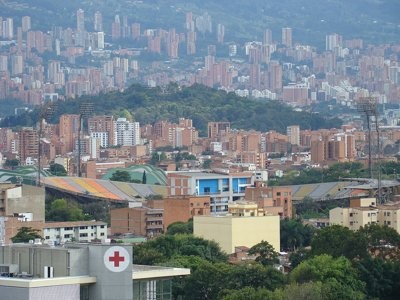

Medellín
Colombia
Medellín, the "City of Eternal Spring", sits in the Aburrá Valley of Antioquia and has become Latin America's premier destination for remote workers and lifestyle investors, drawing a large international community to districts like El Poblado and Laureles. It posted the strongest 2025 price appreciation of any major Colombian city and offers low US-dollar entry prices that comfortably clear Colombia's investor-visa threshold. The headline rental yields are attractive, but they require careful underwriting: short-term-rental supply has surged, average occupancy is modest, and the city has introduced building-level short-let restrictions in El Poblado and Laureles. Net yields run well below the marketed gross figures.
Santa Marta City Guide
Colombia
Santa Marta, the oldest surviving city in Colombia and the capital of Magdalena department, has become one of the country's hottest coastal property markets. Set on the Caribbean where the Sierra Nevada mountains meet the sea, the city combines beaches, the gateway to Tayrona National Park and a fast-improving tourism economy. Prices have risen dramatically, roughly 59% between 2022 and 2025, far outpacing Barranquilla and other regional capitals, with the citywide average reaching around COP 7.3 million per square metre by late 2025 (a median home near COP 450 million, or about USD 118,000). The market is led by El Rodadero, the premier beach district where apartments fetch COP 5-12 million/m2, and the upscale coastal corridor of Playa Salguero, Pozos Colorados and Bello Horizonte. The investment appeal is rental income: well-located short-term rentals can outperform long lets meaningfully, though city-wide short-let occupancy averages only 41-45% with sharp seasonality, strong holiday peaks above 70% but soft off-season midweeks below 30%. Colombia welcomes foreign buyers on equal terms with locals. Investors must weigh genuine risks: Colombian peso volatility, the sustainability of recent double-digit price gains, heavy reliance on tourism seasonality for short-let returns, and infrastructure and utility constraints that vary by neighbourhood.

San Jose
Costa Rica
San Jose is Costa Rica's capital and the heart of the country's central valley -- a temperate, eternal-spring climate region (1,170m elevation) home to ~70% of the country's population. The city is the political, financial, and educational centre of one of Latin America's most stable democracies, with strong English fluency and a long-running US/Canadian expatriate community. Residential prices in prime districts (Escazu, Santa Ana, Curridabat, Sabana, Rohrmoser) range from USD 1,800-3,500 per square metre, with gross yields of 5-8%. Foreign buyers face zero restrictions and can purchase freehold property anywhere in the country -- one of Latin America's most open markets. The Costa Rican colon (CRC) tracks USD relatively closely. For international buyers, San Jose offers political stability, environmental safe-haven status, strong English-speaking professional services, and a long-established North American expat community. The catch: it's not a beach city (the Pacific coast is 1-2 hours away), traffic congestion is severe, and infrastructure is patchier than in major Mexican or Panamanian cities.
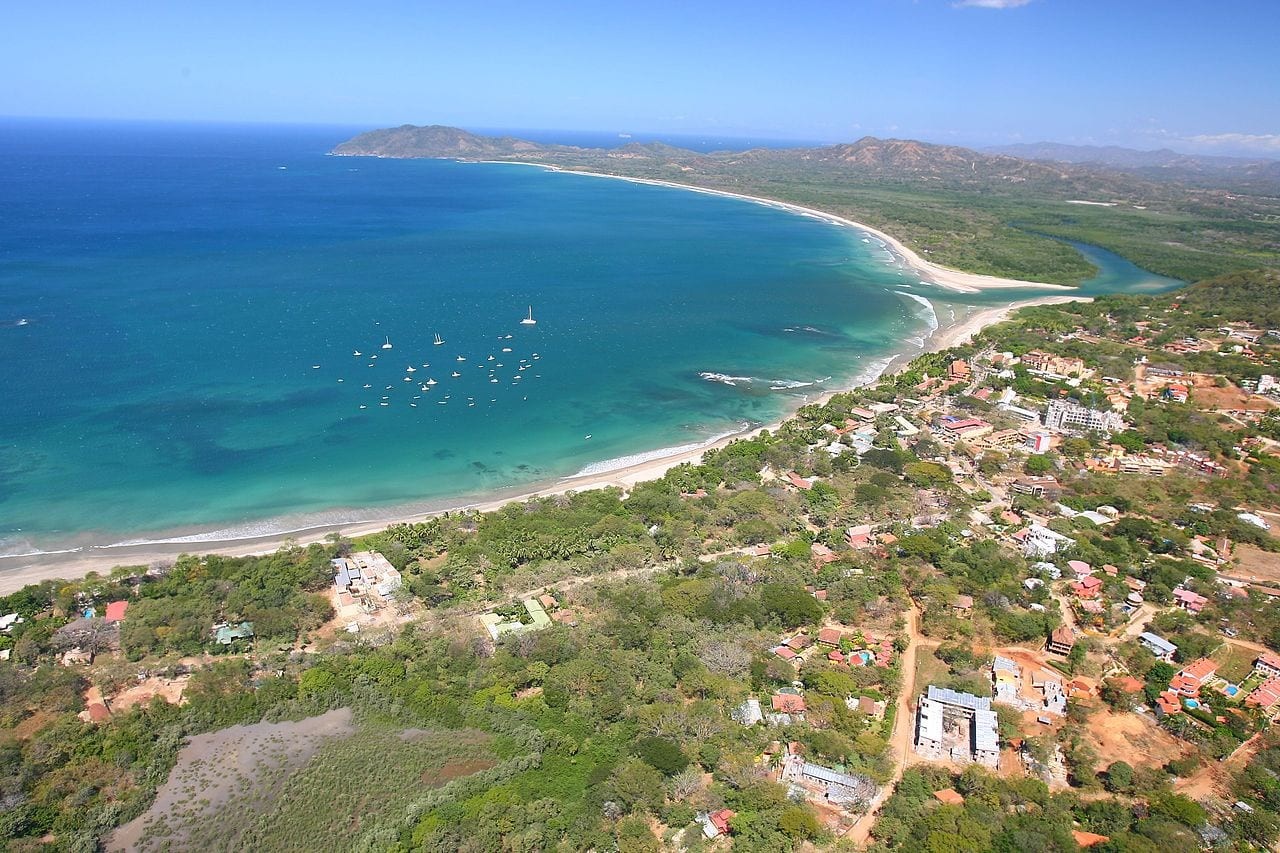
Tamarindo City Guide
Costa Rica
Tamarindo is the established beach-resort capital of Costa Rica's Guanacaste province on the northern Pacific coast, a surf-and-sun town that has matured into one of the country's most liquid second-home and vacation-rental markets. Costa Rica grants foreigners the same property rights as citizens (outside the maritime zone), and Tamarindo's proximity to Liberia's Daniel Oduber international airport, under 90 minutes away with direct North American flights, drives a deep pool of overseas buyers and short-let guests. Pricing spans entry-level condos from around USD 300,000 to single-family villas above USD 400,000, with the luxury segment averaging roughly USD 1.7 million. Beachfront and ocean-view condos near the centre, the Langosta and Playa Grande fringes, and gated hillside communities form the core investment zones. Annual occupancy in this high-tourism corridor typically runs 70-80%, with values appreciating in a steady 5-8% range over the past decade. Vacation-rental income is the primary return driver. Some local brokers cite gross yields of 8-12%, but those figures assume peak-season pricing and high occupancy; a defensible underwriting range is closer to 5-7%. Tamarindo enters 2026 as Guanacaste's most proven coastal market.
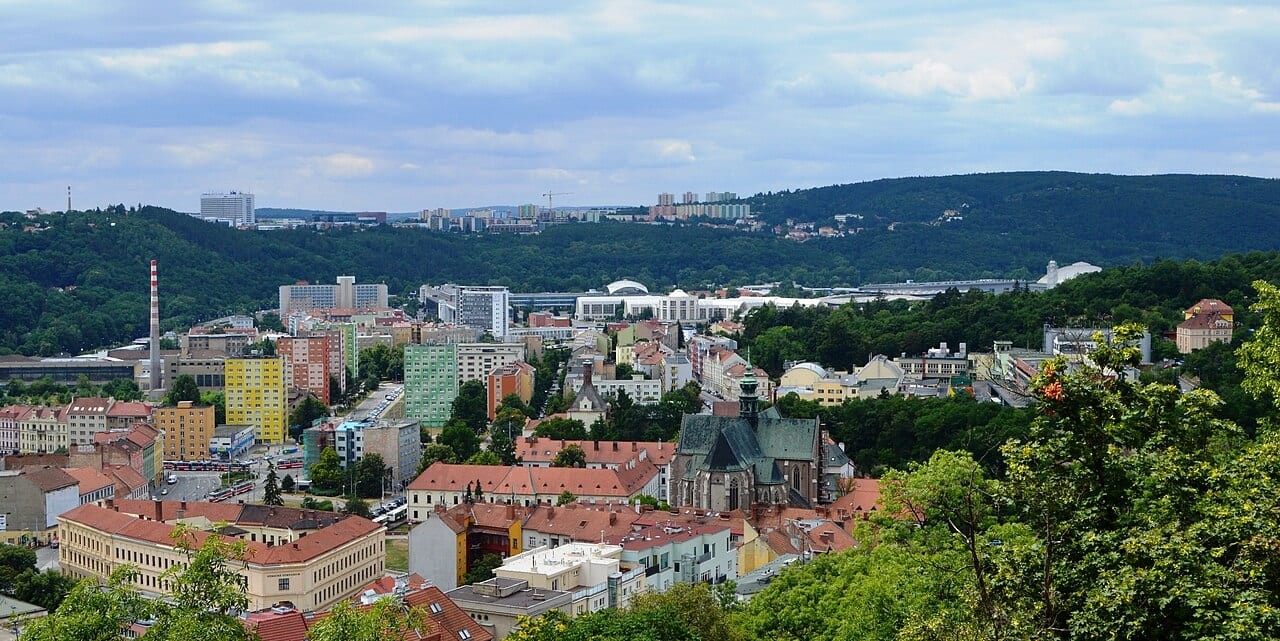

Brno City Guide
Czech Republic
The Czech Republic's second city and its leading technology and university hub, Brno pairs a deep, low-vacancy rental market with appreciation that has lately outpaced Prague in percentage terms. Average apartment prices crossed CZK 116,400 per square metre (about EUR 4,750) in 2025, with a typical flat reaching CZK 9.3 million, still meaningfully cheaper than the capital, where comparable stock sells for roughly 40% more. Demand is driven by the Brno University of Technology, Masaryk University, and the Brno Technology Park, home to IBM, Red Hat, and other multinationals; the student and skilled-professional pipeline keeps the central districts tightly occupied. Kralovo Pole, adjacent to the campuses and tech park, is among the fastest-rising neighbourhoods in the country with 8-12% annual price growth, while the historic centre (Brno-stred), Veveri, and Zabovresky offer characterful pre-war stock. Czech secondary-market prices surged around 21% year-on-year nationally in Q3 2025 amid a supply shortage, and Brno's own new-build asking prices reached CZK 141,000 per square metre. With a population near 384,000 and a structural housing deficit, Brno enters 2026 as the country's strongest regional investment market.
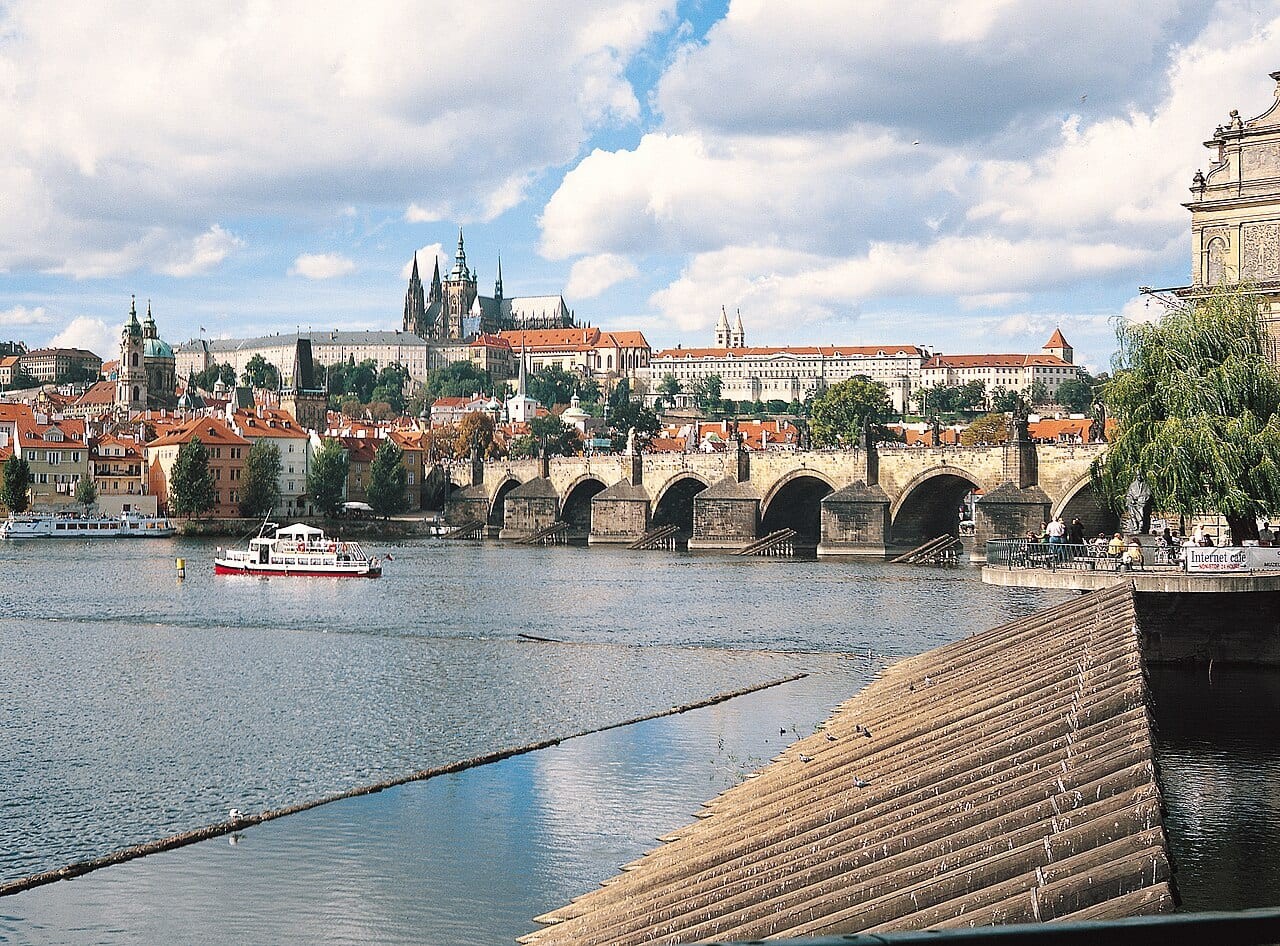
Prague City Guide
Czech Republic
Prague is Central Europe's most expensive residential property market and one of its least affordable relative to local incomes. After a brief 2022–2023 cooling, the market resumed a strong upswing through 2024–2025, with the national house price index growing roughly 10% year-on-year, driven by a chronic housing shortage, slow building-permit approvals, falling mortgage rates and persistent demand. New-build asking prices hit record highs of about €6,700/m² at end-2024, transaction prices for all apartment types reached roughly €5,400/m², and prime central districts (Prague 1 and 2) regularly exceed €8,200/m². The flip side of high prices is low income for investors: Prague's gross rental yields are among the lowest in the CEE region, around 2.8–3.0% citywide, and its price-to-income ratio of roughly 18–19 makes it one of the least affordable capitals in Europe. Prague is therefore a capital-appreciation and capital-preservation play rather than a cash-flow market, buyers accept thin running yields in exchange for a stable EU economy, strong long-term value retention and limited supply that supports prices. For foreign investors the legal environment is unusually open: since 2011 there are no restrictions on foreigners (including non-EU citizens) buying Czech real estate, and the Czech Republic abolished its 4% real-estate-acquisition tax in 2020, lowering entry costs. The main headwinds are the low yields, an emerging crackdown on short-term (Airbnb) letting, and an affordability ceiling that limits how much further prices can run.
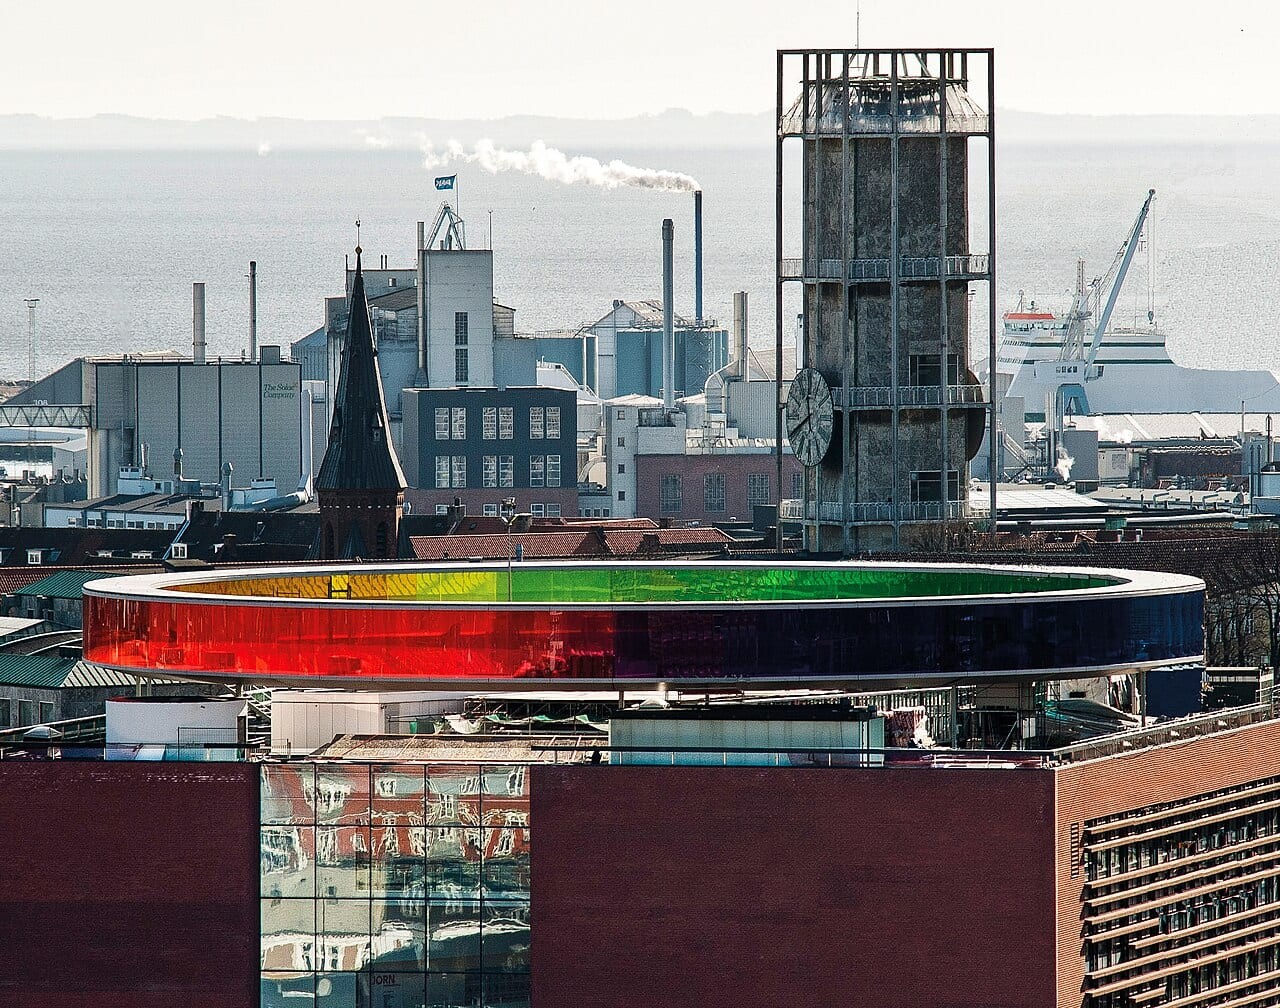

Aarhus City Guide
Denmark
Denmark’s second-largest city and the capital of the Jutland peninsula, Aarhus has built a reputation as the country’s tightest and most resilient rental market. With around 1.2% residential vacancy in Q3 2025, the lowest in Denmark, and a student body anchored by Aarhus University, the city offers investors unusually dependable income relative to the Danish norm. The waterfront Aarhus Ø (Aarhus Docklands), one of Northern Europe’s most ambitious harbourfront regenerations, has reshaped the skyline with new residential towers and become a clear gentrification story, with prices in such districts appreciating an estimated 15–25% over recent years. For yield, investors look inland to student-driven Trøjborg, minutes from the university, and to Viby J, Brabrand, and other outer districts where gross yields reach the 4.5–6% range, against a city average near 4.3% that sits comfortably above Copenhagen’s ~3.0%. The wider Danish market rose roughly 4% nominally over 2025 (about 2% in real terms), a stable backdrop rather than a boom. With an urban population around 301,000 (and a municipality of roughly 378,000), a young demographic profile, and a diversified economy spanning shipping (the Port of Aarhus), life sciences, and education, Aarhus delivers a low-vacancy, income-led entry into the Danish market.
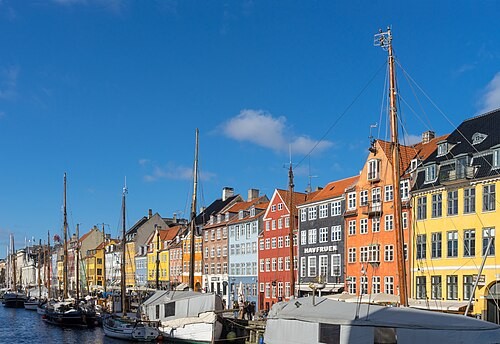
Copenhagen
Denmark
Copenhagen is Denmark's capital, the largest city in Scandinavia by metropolitan population, and consistently a top-5 global liveability ranker. The city is the centre of the Oresund cross-border region (linking to Sweden's Malmo), a major life-sciences cluster (Novo Nordisk, Lundbeck, Genmab), and one of Europe's most committed climate-action capitals. Central districts (Indre By, Frederiksberg, Vesterbro, Norrebro, Osterbro) command DKK 50,000-85,000 per square metre (EUR 6,700-11,400), with gross yields of 3.2-4.5%. The Danish market features a unique andelsbolig cooperative system alongside conventional freehold -- both accessible to foreign buyers, but cooperative purchases need board approval. Mortgage rates have eased since 2024 (Danmarks Nationalbank tracks ECB cuts), supporting renewed price growth after 2022-23 softness. For international buyers, Copenhagen offers EU standing, English-friendly business and education systems, strong rental demand from life sciences and tech tenants, and the lifestyle premium of one of Europe's most liveable cities. The catch: Denmark's foreign-buyer permission requirement applies to non-EU/EEA nationals (a Justice Ministry approval), and high transaction costs (~6-8% all-in).

Roseau City Guide
Dominica
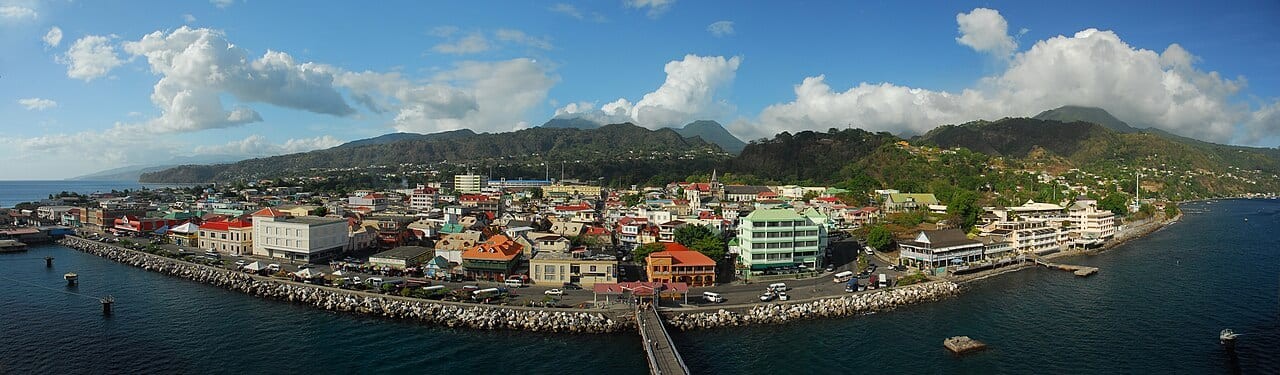
Roseau is the capital and largest city of Dominica, a compact colonial settlement on the island's south-west coast within Saint George Parish, hemmed between the Caribbean Sea and the Roseau River. As the administrative, commercial, and cruise centre of the 'Nature Island', it offers the most developed infrastructure and the deepest pool of jobs and services in the country, which makes it the preferred base for foreign buyers prioritising connectivity over pure beachfront. Prices in Roseau run roughly 10% above the national average, with four-bedroom homes advertised around US$270,000 and broader values spanning US$500 to US$5,000 per square metre depending on location and finish; the nearby Castle Comfort and Wall House areas are the most popular with international investors. Dominica's Citizenship by Investment programme, with an approved real-estate route from US$200,000, is the primary engine of foreign demand and exempts CBI buyers from the Alien Landholding Licence (otherwise 10% of the sale). Rental returns typically run 2–8% depending on type and tourism flow. The principal risks are a small and illiquid market, heavy reliance on CBI policy, and Dominica's exposure to hurricanes and tropical storms.

Punta Cana City Guide
Dominican Republic
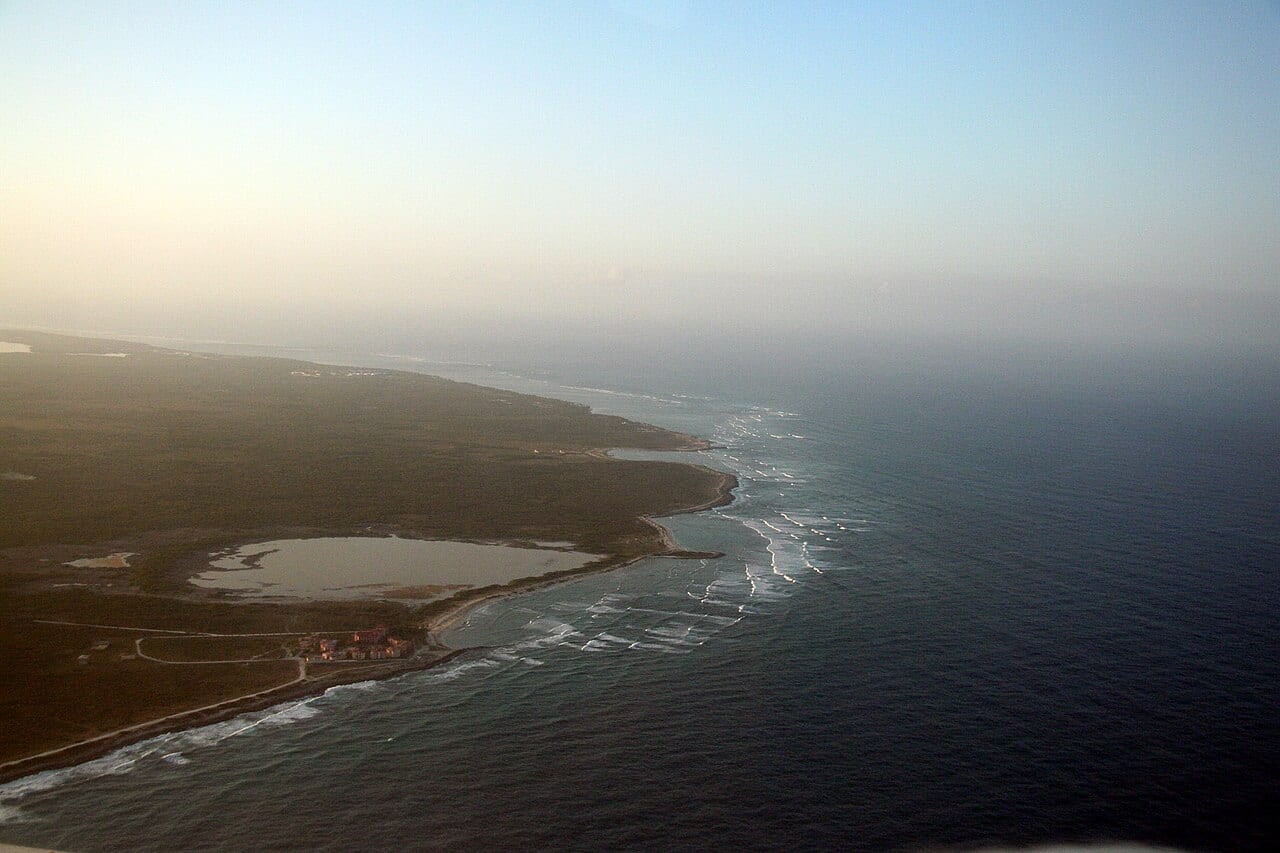
Occupying the easternmost tip of the Dominican Republic, Punta Cana is the Caribbean's leading resort-property market, drawing more than 5 million arrivals a year through its international airport. A combination of white-sand beaches, year-round tourism, hard-currency US-dollar pricing, and an open foreign-ownership regime has made it a magnet for international buyers. Investment concentrates on the high-occupancy short-term rental engine of Bávaro, the ultra-luxury master-planned city of Cap Cana (with its Juanillo and Punta Espada enclaves), the beachfront corridors of Los Corales and El Cortecito, and the gated golf communities radiating inland. Condos average roughly US$1,980-2,100 per square metre - among the more accessible Caribbean entry points - while Los Corales and El Cortecito reach US$2,200-3,500 and Cap Cana villas range from US$1 million to US$4 million-plus. The Dominican Republic welcomed 11.6 million visitors in 2025 with hotel occupancy above 77%, underpinning rental demand. Punta Cana delivers gross rental yields consistently in the 6.75-7.11% range (city average near 7%), with well-managed properties reaching 8% - strong, tourism-driven returns that should be read net of management and seasonality.
Santo Domingo
Dominican Republic
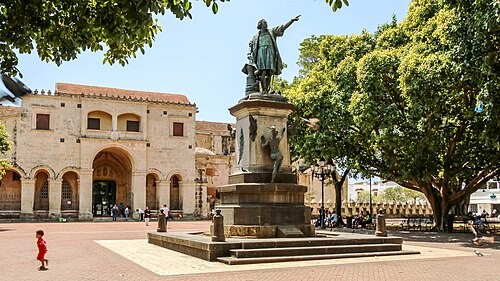
Santo Domingo is the Dominican Republic's capital, the oldest continuously inhabited European-founded city in the Americas (founded 1496), and the financial and political heart of the Caribbean's largest economy by population. The city blends UNESCO-listed colonial architecture (Zona Colonial) with modern high-rise districts (Piantini, Naco) and a growing professional services economy. Residential prices in prime districts range from USD 1,800-3,500 per square metre, with gross yields of 6.5-9.5% -- among the best in the Caribbean for long-let. Foreign buyers face no restrictions on property ownership in DR, and the country offers a very accessible residency-by-investment programme (USD 200,000 qualifying investment). For international buyers, Santo Domingo offers some of the Caribbean's best yields, open foreign ownership, an accessible residency programme, and growing professional services and tourism economies. The catch: Dominican peso (DOP) volatility, slower legal/transaction processes than Panama or Costa Rica, and infrastructure quality varies sharply by district.

Cuenca
Ecuador
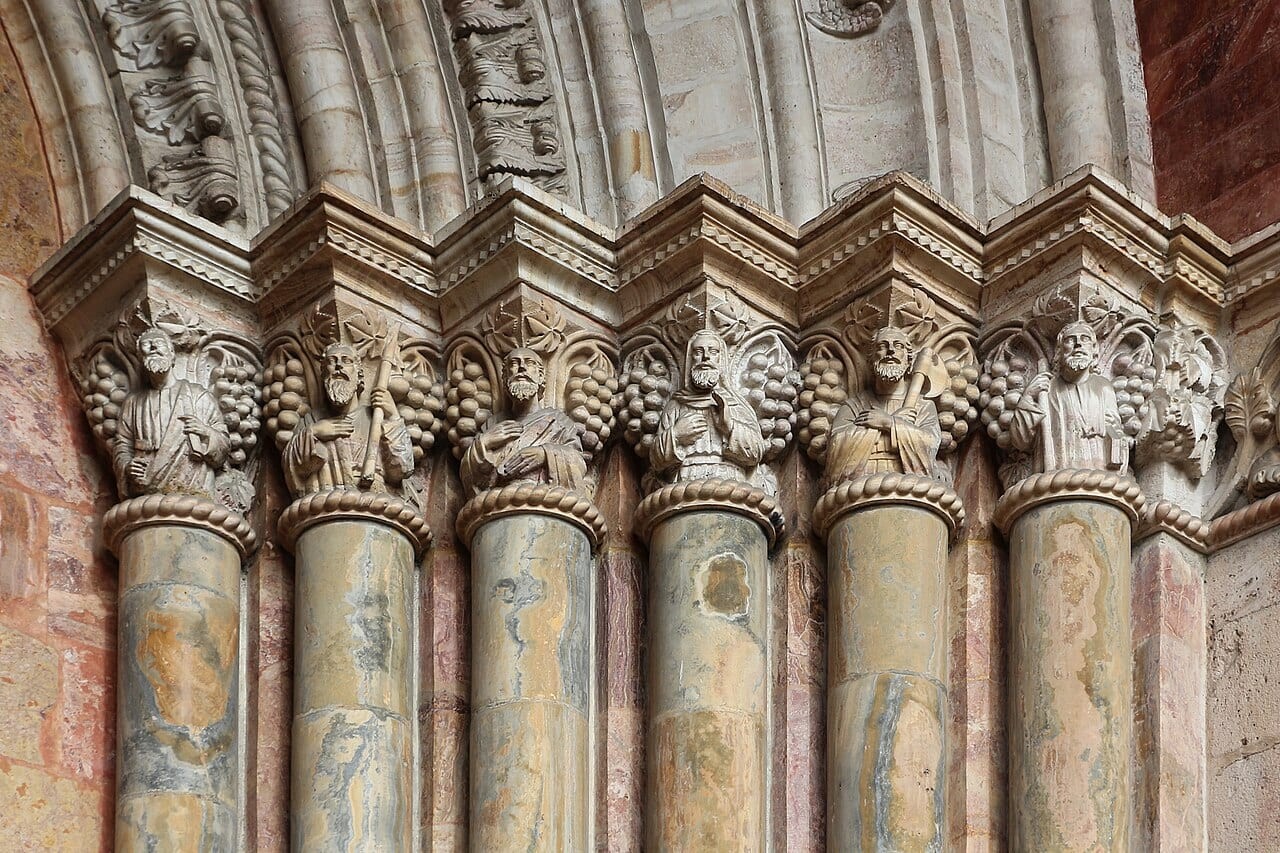
Cuenca, a UNESCO World Heritage city in Ecuador's southern Andes, is the country's premier expat and retirement destination and its most expensive residential market by land value. Median asking prices sit near $1,230/m² in 2026, with prime apartments on Av. Ordóñez Lasso and around El Centro reaching $1,300/m². Demand surged roughly 32% in 2024 (Plusvalía data), and the market has held firm through national uncertainty thanks to a deep, dollar-denominated expat buyer base. Gross rental yields on well-located apartments run 7–8.5%, among the strongest in Ecuador, driven by long-stay retirees and short-term visitors to the colonial core. Ecuador uses the US dollar (since 2000), removing currency risk for foreign buyers. Foreigners own property on identical legal footing to citizens, no trusts, partners, or licences required, and Cuenca sits well outside the 50km border and coastal restriction zones. A property assessed at roughly $48,200 (100× the 2026 minimum wage) qualifies the buyer for the Inversionista investor-residency visa, a two-year temporary permit leading to permanent residency in about four years. Annual property taxes commonly run under $300. With heritage protections capping new central supply, scarcity supports steady 3–5% appreciation on prime stock.
Guayaquil
Ecuador
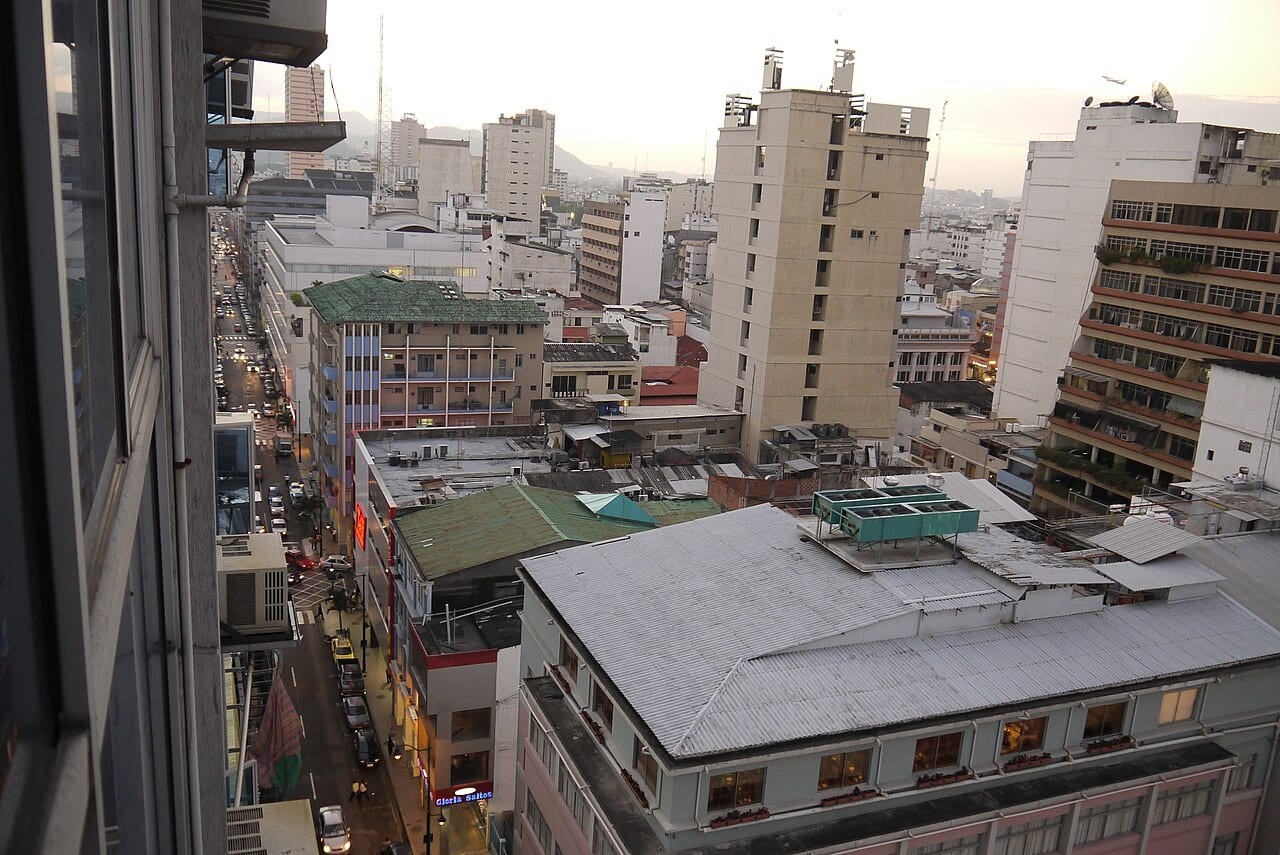
Guayaquil, Ecuador's largest city and principal port, is the country's commercial and industrial powerhouse, generating a deep, business-driven property market distinct from the highland capital. Investor activity concentrates in secure, high-end enclaves: the gated suburb of Samborondón, the waterfront redevelopments of Puerto Santa Ana and Ciudad del Río, and the modern north. In 2026, two-bed apartments in Puerto Santa Ana run $80,000–$150,000, while three-bed homes in Samborondón gated communities range $180,000–$350,000; metro two-bed asking prices average near $112,000. Gross rental yields sit around 6–7.5% in prime zones, supported by corporate staff, expats and professionals seeking safe addresses. Ecuador's full dollarization removes currency risk, and there are no restrictions on foreign ownership, land and built property can be held under personal or corporate names. Guayaquil lies far from the 50km border zone. A purchase near the $48,200 threshold (100× the 2026 minimum wage) qualifies for the Inversionista investor-residency visa. With dollar stability, cost competitiveness versus regional peers and concentrated demand for secure stock, prime Guayaquil offers moderate but dependable appreciation of roughly 3–4% with strong cash flow in the city's gated and waterfront districts.
Quito
Ecuador
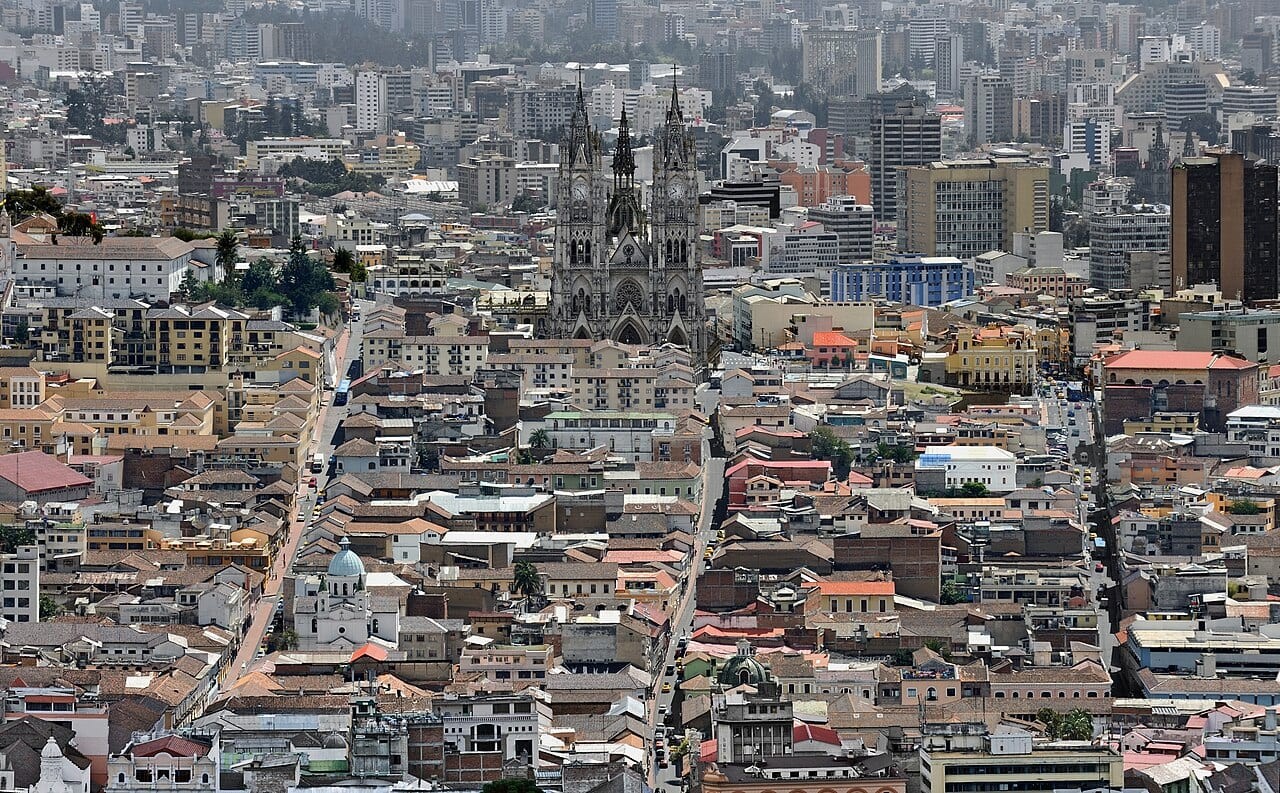
Quito, Ecuador's high-altitude capital, anchors the country's largest and most diverse property market, spanning a UNESCO-listed colonial center, modern financial districts and affluent valley suburbs. Average pricing sits near $1,330/m² in 2026, cheaper than Lima ($1,640) or Bogotá ($1,410), while gross rental yields range from about 5.8% in the central core to nearly 9–10% in outer districts, with prime modern apartments around 6–7%. As the seat of government, NGOs and multinationals, Quito offers the country's deepest pool of corporate and diplomatic tenants, concentrated in González Suárez, La Carolina and the Cumbayá–Tumbaco valley. Ecuador's full dollarization (since 2000) eliminates currency risk, and foreigners buy on identical terms to citizens, with no trusts or partners required; Quito lies far from the 50km border and coastal restriction zones. A purchase near the $48,200 threshold (100× the 2026 minimum wage) qualifies for the Inversionista investor-residency visa, leading to permanent residency in roughly four years. With political and pro-business stabilization under the Noboa agenda, prime assets are forecast to appreciate around 3–5% annually alongside 5%+ income yields, making the capital Ecuador's core blend of liquidity and cash flow.
Salinas
Ecuador
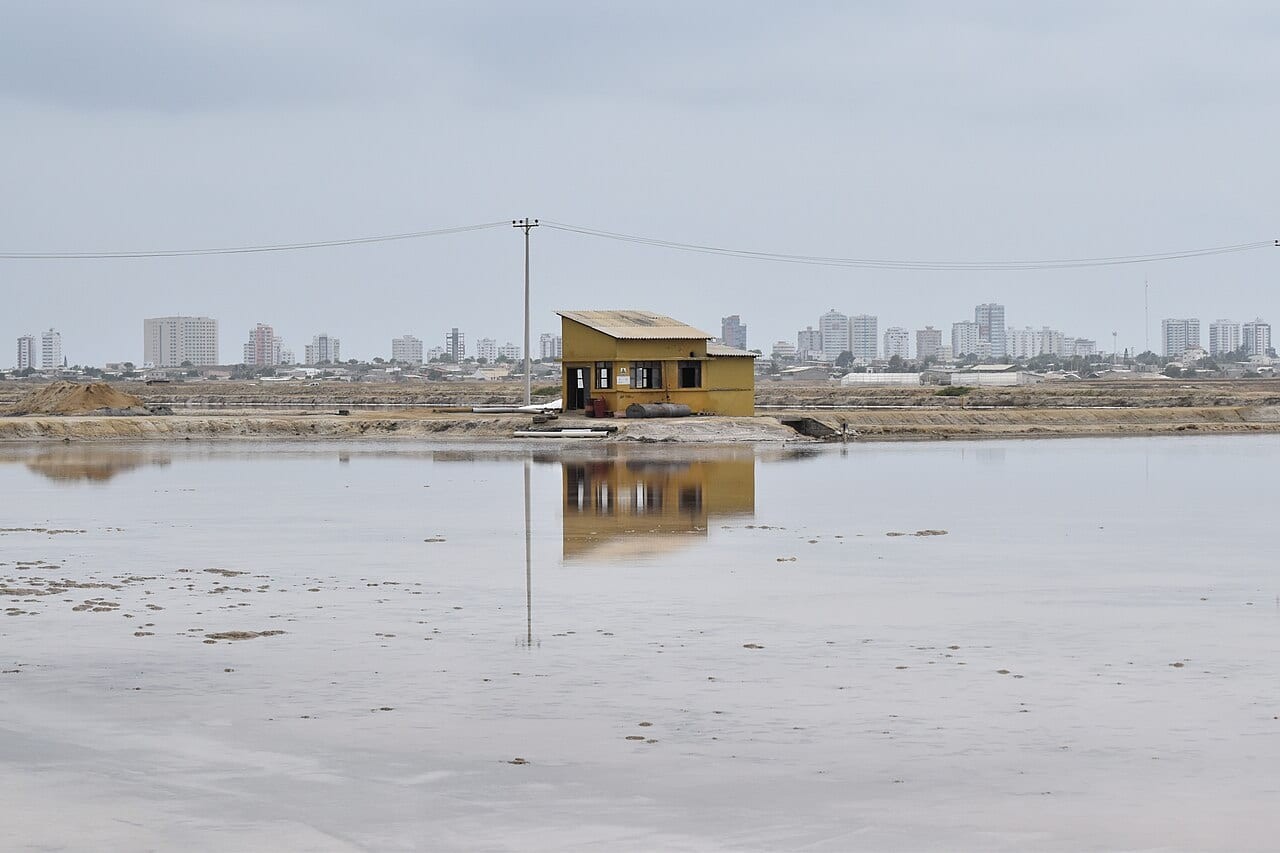
Salinas, on Ecuador's Santa Elena peninsula, is the country's most popular beach resort and a fast-rising expat favorite, offering oceanfront and ocean-view property at prices far below comparable Latin American coasts. In 2026 the median condo sells around $149,000 at roughly $1,255/m², with one-bed ocean-view units near $70,000–$120,000 ($79,500 average), two-beds around $113,000, and three-beds near $172,000. As Ecuador's top domestic beach destination, Salinas supports active vacation-rental demand, with well-managed oceanfront condos achieving 6–9% gross yields in peak season. Ecuador's full dollarization removes currency risk for foreign buyers. Foreigners own on the same footing as citizens; Salinas sits outside the 50km border zone, and while some undeveloped coastal land within roughly 8km of the shoreline carries municipal restrictions, these do not affect Salinas's built condos and titled urban beachfront. A purchase near $48,200 (100× the 2026 minimum wage) qualifies for the Inversionista investor-residency visa. With reasonable beachfront entry prices, strong seasonal rental demand and growing expat interest, Salinas offers an accessible dollar-priced coastal play with 3–5% appreciation and standout cash-flow potential in its prime beach zones.

Alexandria City Guide
Egypt
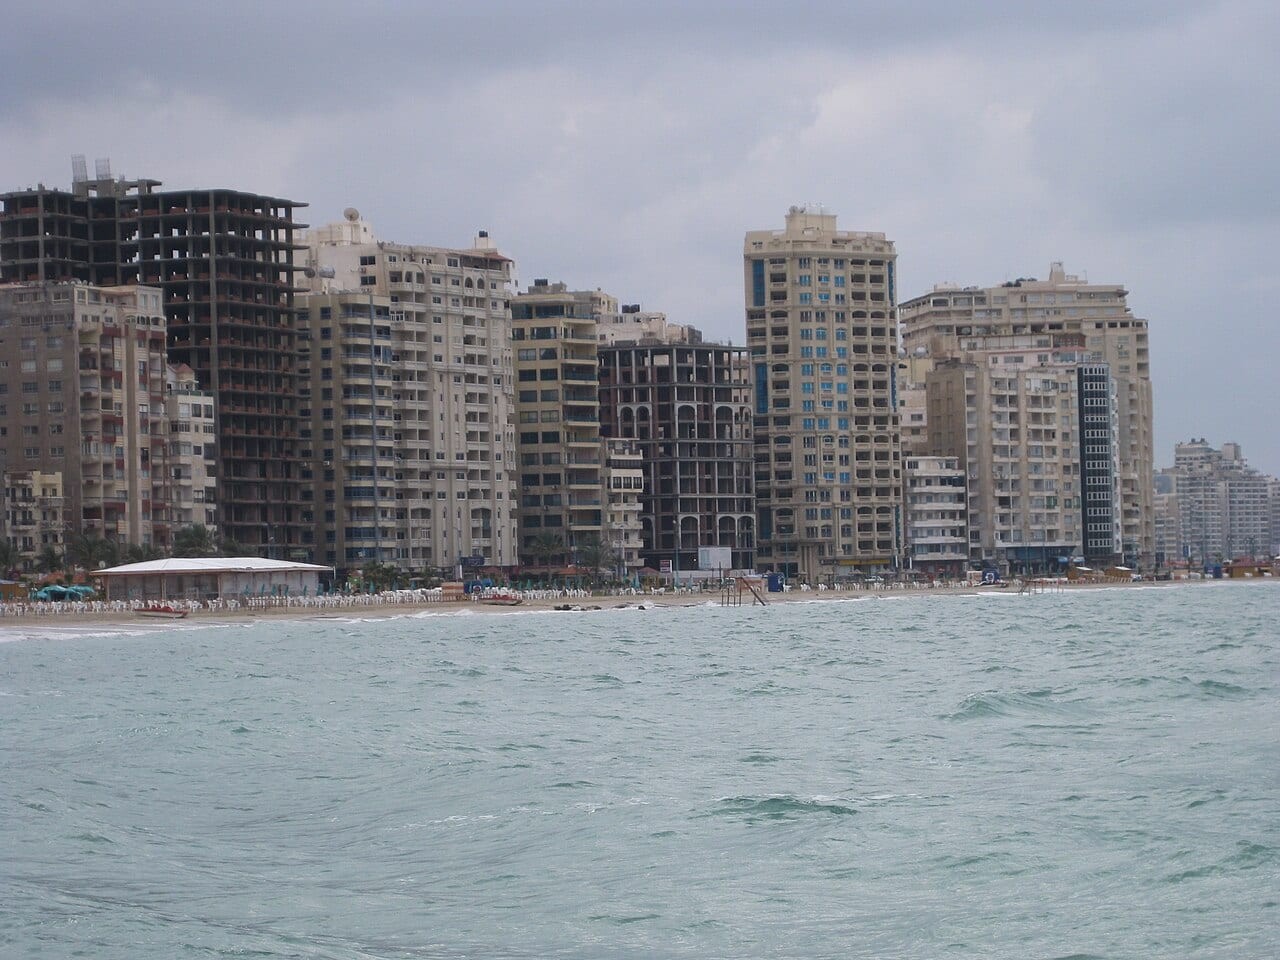
Egypt's Mediterranean capital and its second city, Alexandria pairs a 2,300-year cultural legacy with one of the country's most supply-constrained residential markets. Stretching along a 30-kilometre Corniche, the city blends established upmarket districts such as Smouha, Stanley, and Kafr Abdo with the major new-build catalyst of Sawary Alexandria and the expanding western suburbs. Unlike the seasonal North Coast resort belt, Alexandria functions as a deep, year-round residential market driven by long-term tenancy, a large domestic professional base, and a population projected to grow at roughly 5.1% CAGR through 2035. Nominal prices have moved sharply in the high-inflation Egyptian pound environment - the average apartment now sits near EGP 7,950 per square metre (about US$171), up around 5% year-on-year, while villa values rose far faster off a low base. Persistent undersupply relative to demand keeps upward pressure on prices across most neighbourhoods. For international and diaspora buyers, Alexandria offers gross apartment yields in the 4-6% range, hard-currency upside via the weak pound, and a more stable, end-user-led market than Egypt's tourism-driven coastal hotspots.
Cairo
Egypt
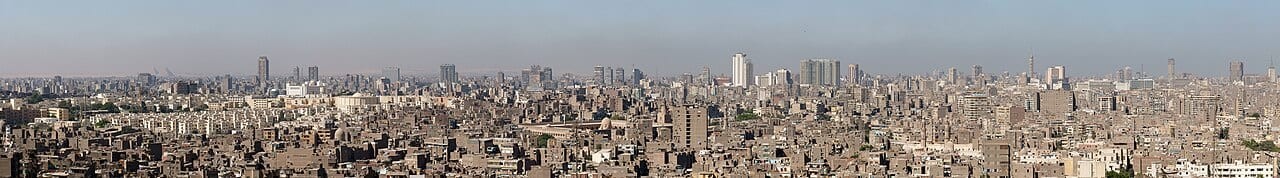
Cairo is Egypt's capital, the Arab world's largest city by population (~22 million in the greater metro), and one of the Middle East's most important historical, political and cultural centres. The market is currently being reshaped by the government's New Administrative Capital (NAC) project, the country's IMF-backed currency liberalisation, and a wave of post-2022 EGP devaluation that has created compelling foreign-currency entry points. Residential prices in prime districts (Zamalek, Maadi, Heliopolis, New Cairo, Sheikh Zayed) range from EGP 35,000-90,000 per square metre, with gross yields of 7-10% in USD-priced compound segments. The 2024 currency liberalisation (EGP devalued to ~50 per USD) made Egypt one of the cheapest major emerging markets globally on a USD-priced basis. International buyers face no restrictions and can purchase freehold property anywhere in the country. For international buyers, Cairo offers extreme value post-devaluation, very strong gross yields, a 100-million-strong population catchment, and zero foreign-ownership restrictions. The catch: EGP volatility is significant, transaction processes are bureaucratic, and political/macro risk is materially higher than Gulf markets.
Giza City Guide
Egypt
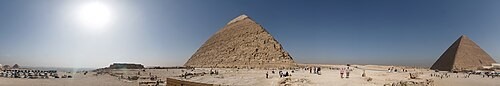
Giza sits on the west bank of the Nile across from Cairo, home to the Pyramids and Sphinx and, since November 2025, the Grand Egyptian Museum (GEM), the world's largest single-civilisation museum, which is projected to help draw more than 25 million tourists to the plateau in 2026. The governorate spans dense older districts such as Haram and Faisal and the planned satellite of 6th of October City, which together with New Cairo accounted for over 40% of Egypt's new residential development in 2024. Foreign buyers should weigh two hard constraints: Law No. 230 of 1996 caps non-Egyptians at two residential units (each up to 4,000 m2) with a five-year resale lock, and the Egyptian pound's sharp devaluation from March 2024 means headline EGP price growth of 60-150% in some Giza districts is largely inflation rather than real US-dollar gains. Gross residential yields are modest at roughly 5-8%, and policy rates of 27-30% keep local mortgage demand thin.
Hurghada City Guide
Egypt
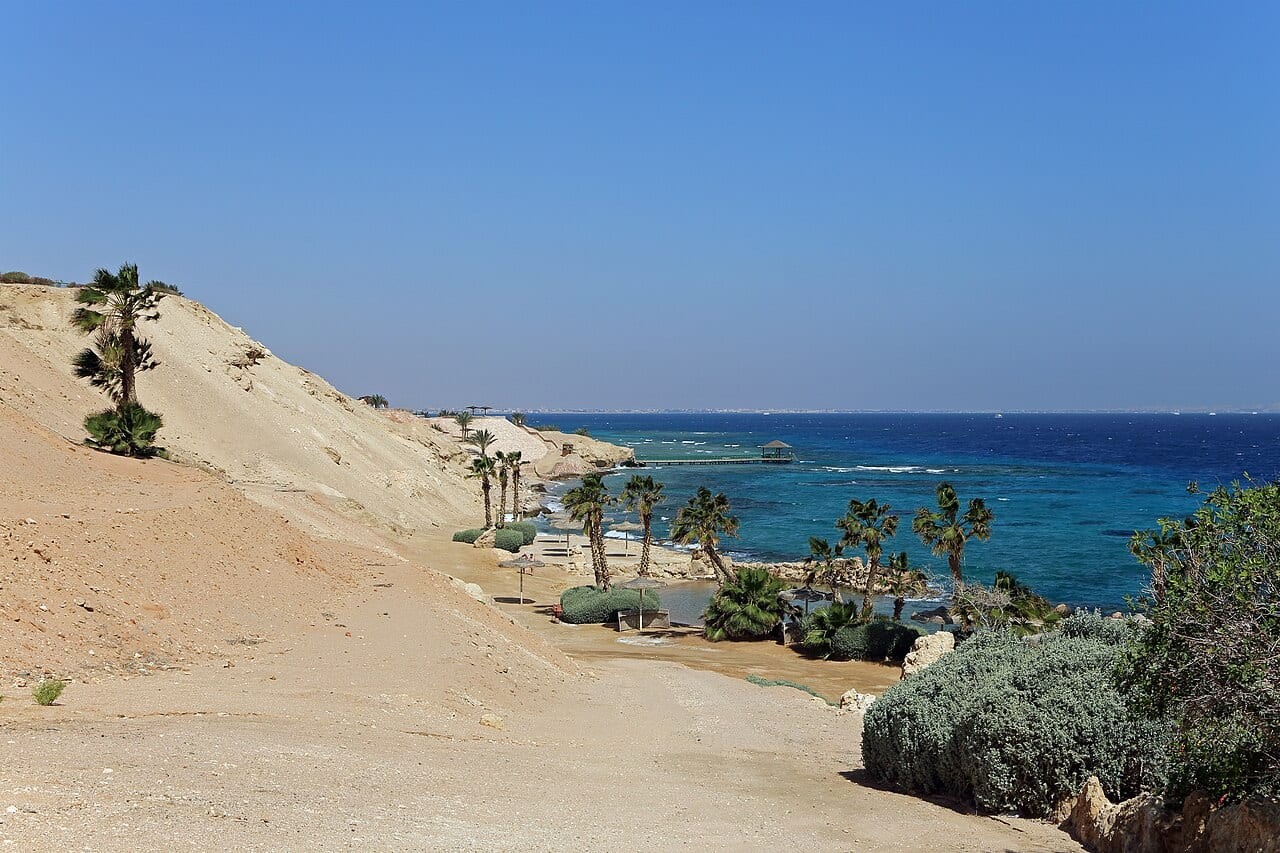
Hurghada stretches along Egypt's Red Sea coast in the Red Sea Governorate and is the country's leading beach-resort property market, anchored by year-round sunshine, diving and a tourism sector that helped Egypt welcome nearly 19 million visitors in 2025. Resort communities such as Sahl Hasheesh and Makadi Bay sell predominantly to foreign buyers at US-dollar prices, where the same Law No. 230 of 1996 two-unit cap and five-year resale lock apply. The draw is the short-let economy: furnished resort apartments and beachfront units generate a realistic 6-8% gross annual yield, with well-managed Marina and Sahl Hasheesh stock occasionally cited toward 8-10% in peak season, though such figures should be treated as marketing-optimistic rather than guaranteed. Prices have risen 10-15% over the past year, and because foreign-resort transactions are largely dollar-denominated they are partly insulated from the EGP devaluation that distorts Cairo and Giza data.
Sharm El Sheikh
Egypt
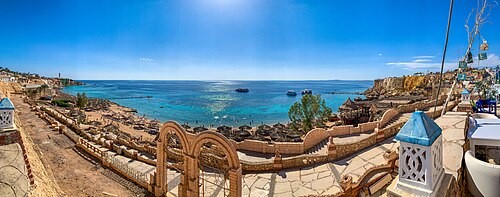
Sharm El Sheikh is Egypt's premier Red Sea resort city, located on the southern tip of the Sinai Peninsula. The city has been one of the Mediterranean basin's most successful resort destinations for three decades, drawing 5-7 million annual visitors (pre-COVID levels now restored) and serving as a primary diving, beach, and conference destination. Residential prices in beach-adjacent compounds (Naama Bay, Hadaba, Nabq, Sharks Bay) range from EGP 30,000-65,000 per square metre (USD 600-1,300), with strong short-let / holiday rental yields of 8-12% gross when properly managed. The market is highly compound-driven -- foreign buyers almost exclusively purchase in serviced gated developments with pool, beach access, and rental management. For international buyers, Sharm offers cheap entry, strong short-let yields, zero foreign ownership restrictions, and exceptional Red Sea natural amenity. The catch: seasonality (winter peak, summer slow), heavy reliance on UK/Eastern European tour operators, and sporadic regional security headlines that can damage tourist arrivals.