City guides
City guides (402)
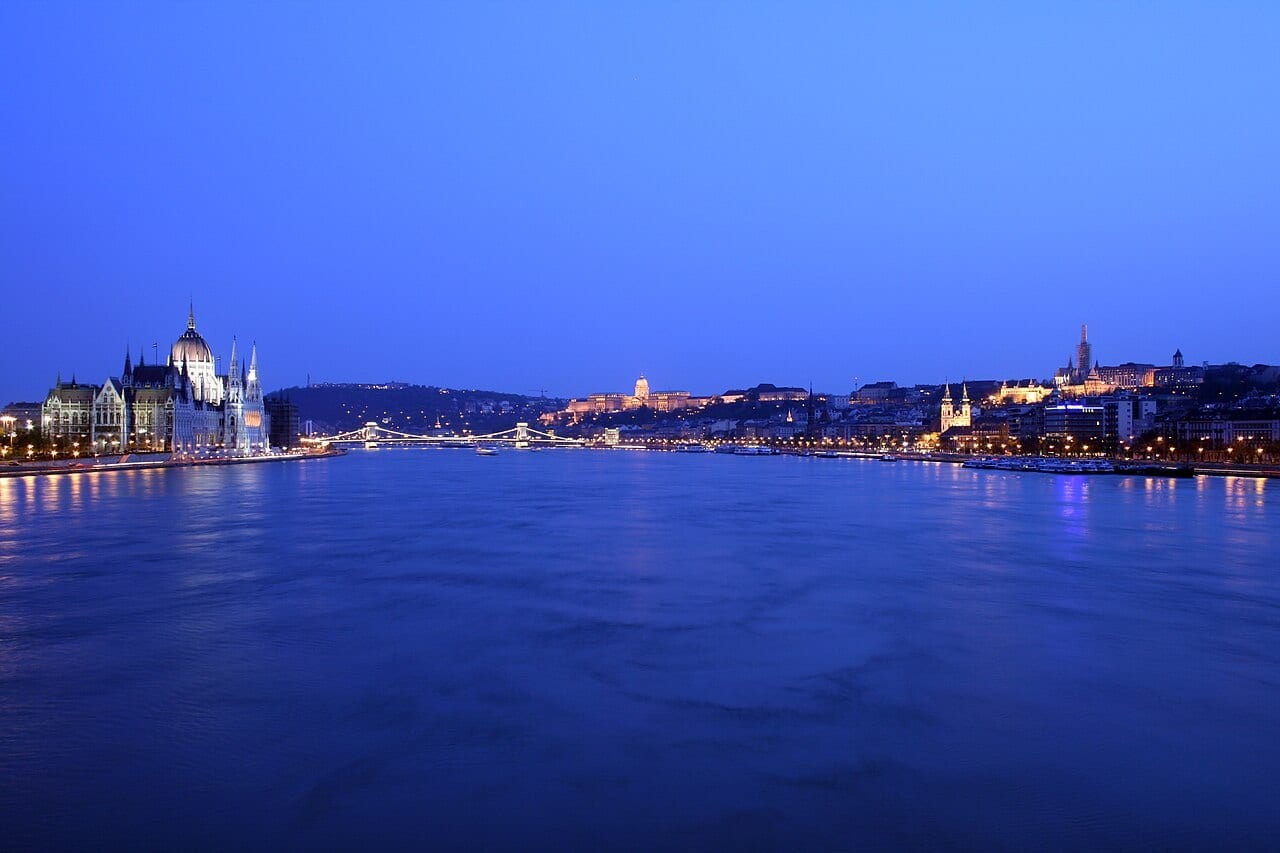

Budapest City Guide
Hungary
Budapest, Hungary's capital (~1.7 million in the city, ~3.3 million metro), straddles the Danube where the historic hills of Buda meet the flat commercial grandeur of Pest. The riverfront panorama, the neo-Gothic Parliament, the Buda Castle Quarter and the Danube embankments, is a UNESCO World Heritage Site, and Andrássy Avenue with its 1896 M1 metro (continental Europe's first underground) was added in 2002. Buda is leafy, hilly and residential; Pest is the dense, walkable urban core where commerce, nightlife and the bulk of the apartment stock concentrate. The city is the world's de-facto 'thermal-bath capital', sitting on 100+ hot springs that feed historic baths (Széchenyi, Gellért, Rudas), a year-round tourism driver behind one of Central Europe's strongest short-stay rental markets. Tourism, EU membership and comparatively low entry prices have made inner Pest a magnet for both lifestyle buyers and yield-seekers. Critically, Hungary uses the forint, NOT the euro, so euro-denominated returns carry currency risk. The market is in regulatory transition: a citywide moratorium on new short-term-rental registrations runs through 2026, District VI has enacted Hungary's first outright Airbnb ban (effective 1 January 2026), and the EU's STR registration regime applies from 20 May 2026. Note also that Hungary's Guest-Investor 'golden visa' no longer includes a direct residential-property option (the €500,000 route was abolished on 15 January 2025), buying an apartment does NOT grant residency. Prices have nonetheless risen sharply, Budapest was among Central Europe's fastest-appreciating capital markets in 2025.
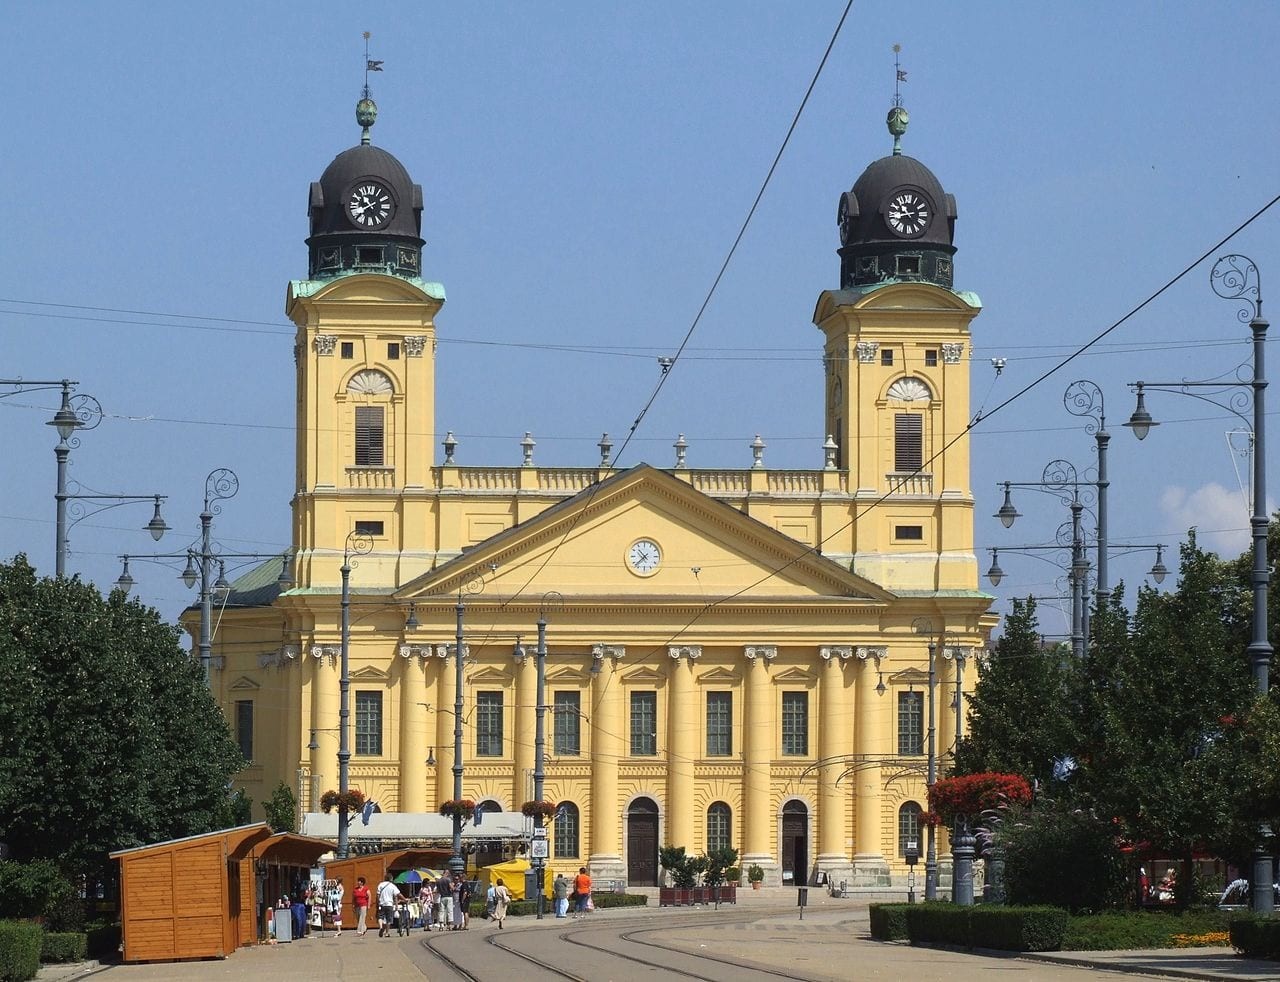
Debrecen City Guide
Hungary
Hungary's second-largest city and the capital of the Northern Great Plain, Debrecen has transformed from a historic university and church town into one of Central Europe's most dynamic industrial-investment stories. The catalyst is BMW: the carmaker's roughly EUR 2 billion iFactory plant, the company's newest, producing the all-electric Neue Klasse iX3, officially opened in late 2025, creating more than 2,000 jobs and triggering a wave of supplier investment and housing demand. With a population around 200,000, Debrecen remains markedly more affordable than Budapest, with average prices near HUF 882,000 (about EUR 2,200) per square metre, though brick-apartment values recently crossed the symbolic one-million-forint mark. The wider Northern Great Plain region led Hungary on price growth in 2025, posting annual gains of roughly 13-17% on the back of industrial investment. Rental yields in Debrecen are among the most attractive in Hungary, with the broader market averaging around 5% and larger or well-located units reaching 6% or more. Demand is anchored by the University of Debrecen, one of the country's largest, the major teaching hospital, and the new automotive workforce. As a forint market, Debrecen carries currency considerations for foreign buyers but offers genuine industrial-led upside.
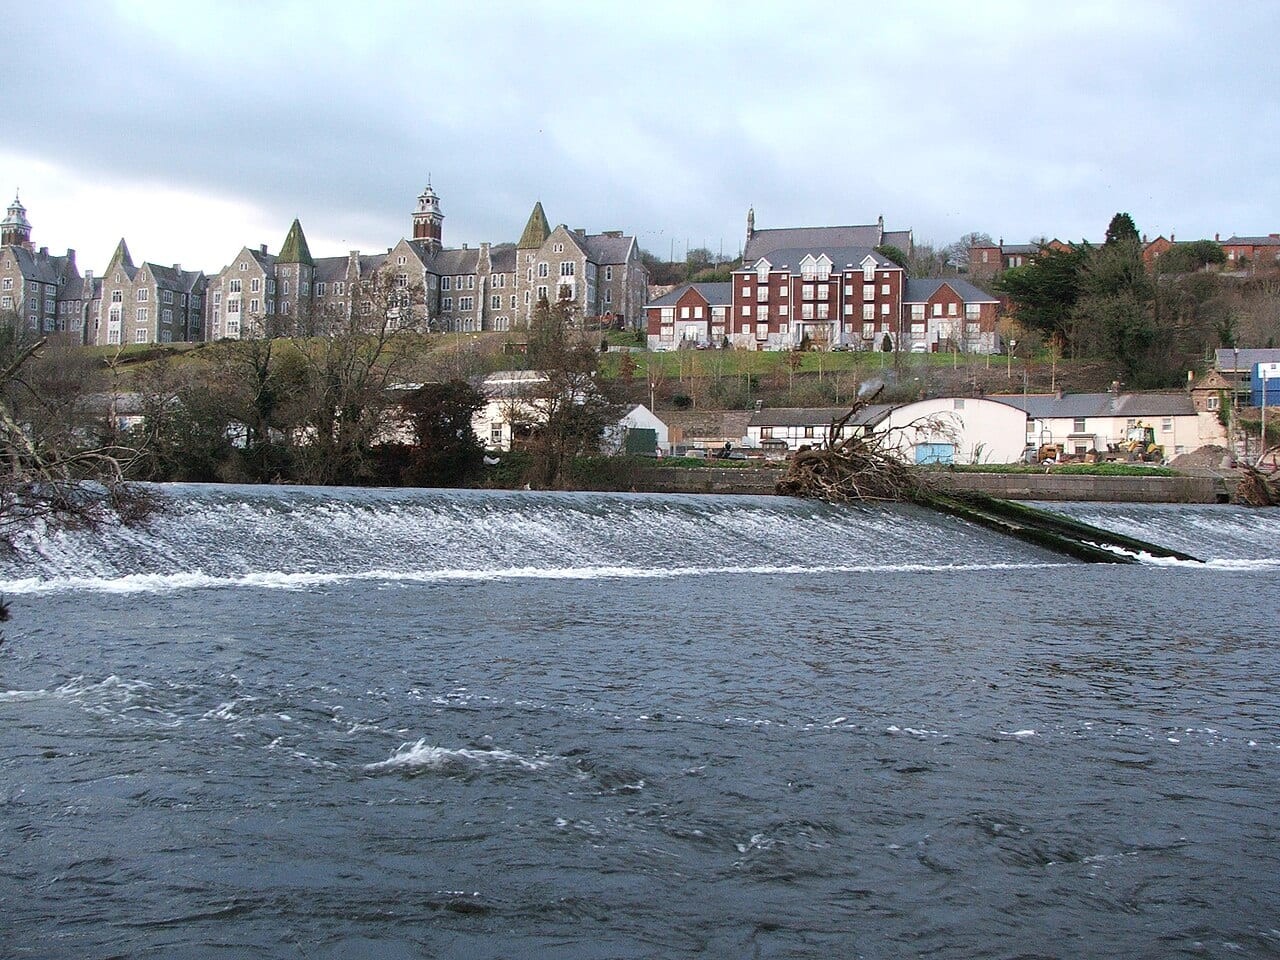

Cork City Guide
Ireland
Ireland’s second city and the capital of the south-west, Cork has become one of the country’s most compelling investment markets, combining a fast-growing tech and pharma employment base with entry prices well below Dublin’s. Global names including Apple (whose European HQ is in Cork), Pfizer, Stryker, and a cluster of pharmaceutical manufacturers anchor a high-wage economy that is drawing population and pushing rents higher. Cork city house prices rose around 7.4% in the year to late 2025 (with the wider South-West region up 9.6% in October 2025), and the average Cork city home now costs roughly €361,500. Crucially, Cork carries some of the strongest rental yields of any major Irish city: city-centre apartments and studios reach gross yields in the region of 7%, well ahead of comparable Dublin returns, though yields fall sharply toward 3% on larger suburban family houses. Income is underpinned by an exceptionally tight rental market, Irish rental availability hit a near-twenty-year low in early 2026, just two-fifths of the 2015–19 average. The Docklands regeneration and continued FDI-driven jobs growth give Cork a clear catch-up narrative versus the capital. With strong fundamentals but a high-yield headline that reflects scarcity and a structural housing shortage, Cork rewards selective, location-led buying.
Dublin
Ireland
Dublin is Ireland's capital and the only English-speaking capital fully inside the EU and Eurozone post-Brexit -- a structural advantage that has anchored a decade of strong economic, demographic, and property market growth. The city is home to the European HQs of Google, Meta, Apple, Microsoft, Stripe, LinkedIn, TikTok, Pfizer, and most of US Big Pharma, alongside a thriving domestic finance and professional services sector. Central residential (Ballsbridge, Donnybrook, Sandymount, Rathmines, Ranelagh, City Centre) commands EUR 6,000-11,500 per square metre, with gross yields of 4.5-6.5%. Dublin's housing supply consistently runs 30-40% below demand -- one of the worst structural shortfalls in any developed-world capital -- supporting double-digit rental growth in 2024-25. For international buyers, Dublin offers Eurozone safety with English as the primary language, deep institutional tenant demand from US tech and pharma multinationals, and one of Europe's most resilient capital growth profiles. The catch: prices have already run 80%+ since 2014, transaction costs are 5-7%, and the rental sector is tightly regulated (Rent Pressure Zones cap most rent increases at 2% or HICP).

Haifa City Guide
Israel
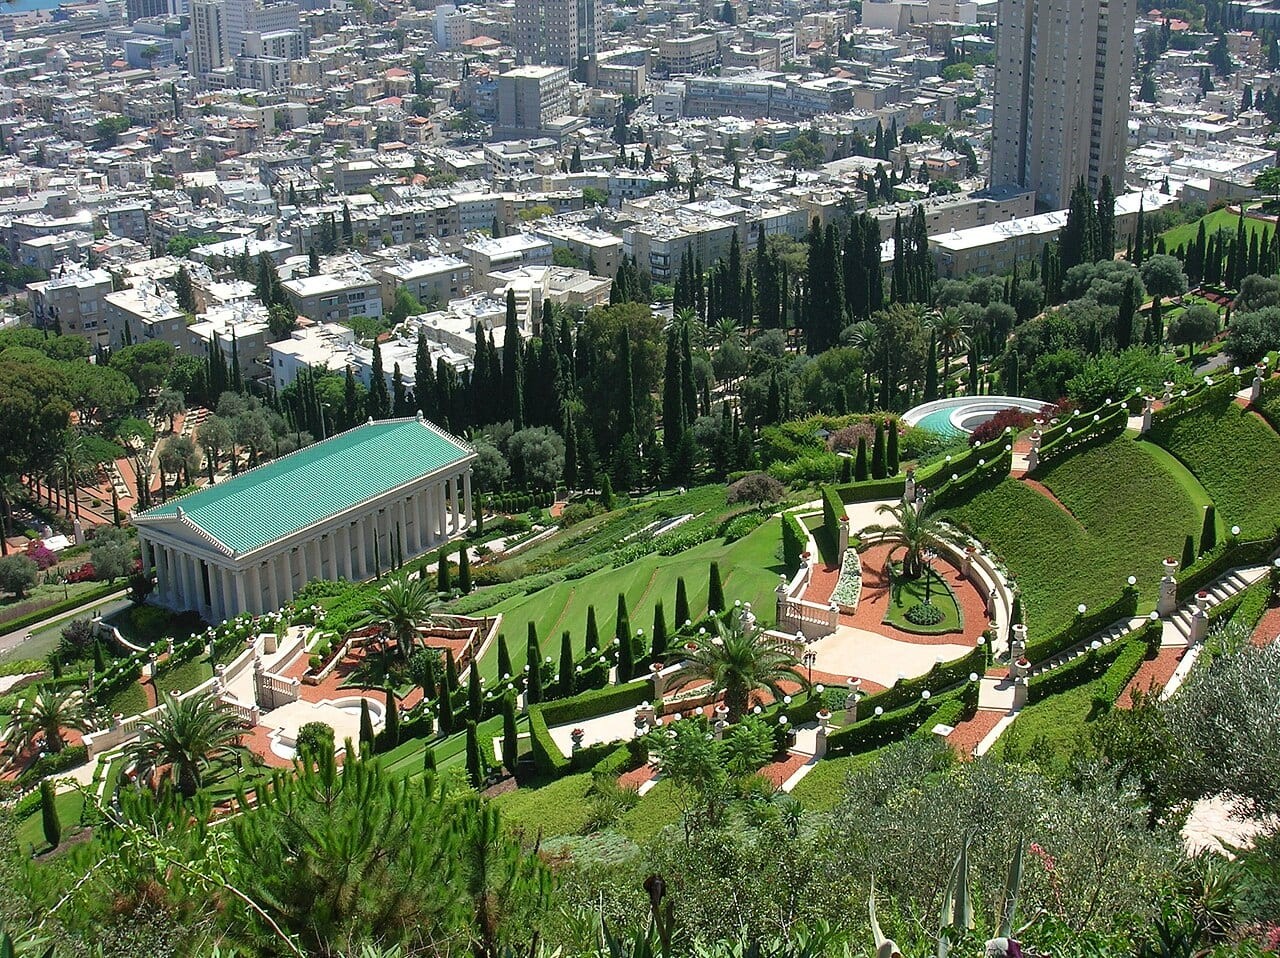
Israel's third-largest city and the economic anchor of the north, Haifa cascades down the slopes of Mount Carmel to a major Mediterranean port, blending a deep-water shipping and logistics hub with one of the country's most important technology and academic ecosystems. The Technion (Israel Institute of Technology) and the University of Haifa underpin a research-driven economy that hosts R&D centres for Intel, Google and Amazon, while the city is celebrated for the UNESCO-listed Baha'i Gardens and a famously mixed, tolerant social fabric. With a population around 285,000, Haifa is the most affordable of Israel's major cities, with prices roughly ILS 12,000-25,000 per square metre. The market showed strong momentum in early 2025: average residential prices rose about 9.4% year-on-year in Q1 to ILS 2.16 million, with price per square metre up 10.8% and transaction volume up 14.1%. Gross rental yields, while modest by global standards, are attractive for Israel at around 3.4-3.9% citywide, rising higher near the Technion where student-housing occupancy exceeds 97%. Key districts include the upscale Carmel Center, the gentrifying Hadar and German Colony, and the Technion-adjacent Neve Sha'anan, giving investors a more accessible entry into Israel's resilient housing market than Tel Aviv.

Tel Aviv City Guide
Israel
Tel Aviv-Yafo is the Mediterranean economic and cultural capital of Israel and the heart of 'Startup Nation', a dense tech and venture-capital hub where glass towers sit beside the UNESCO-listed 'White City' of 4,000+ 1930s Bauhaus buildings. Fronting a scarce, supply-constrained beachfront, it is consistently ranked among the world's most expensive cities, with the highest residential prices in the Middle East. For investors it is a global-city, capital-growth and lifestyle market: prices average roughly €15,750/m² citywide and are steadying after the wartime slump, with the new metro reshaping accessibility. Yields are thin (~2.5–3.5%), so the case is scarcity-driven appreciation rather than income.

Bologna City Guide
Italy
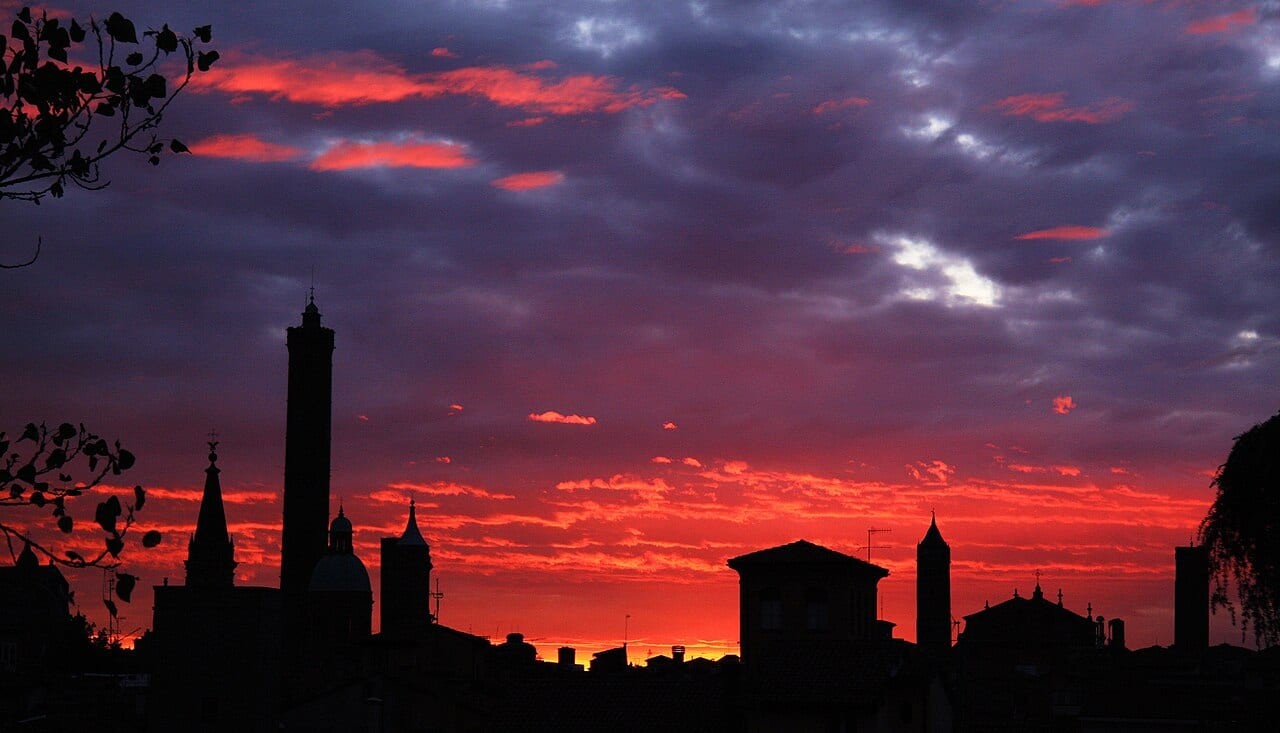
Bologna, capital of Emilia-Romagna and home to the world's oldest university, is one of Italy's most resilient and rental-driven property markets. The city of roughly 391,000 (with more than a million in its metropolitan province) sits at the heart of the national rail network, two hours from both Milan and Florence, and combines a perfectly preserved medieval Centro Storico (Europe's largest network of porticoes) with a diversified economy spanning education, research, advanced manufacturing and a globally renowned food cluster. For investors the defining feature is rental demand: a vast student population and constant inflow of researchers and professionals keep vacancies minimal, with landlords often fielding multiple applications within hours of listing. Average asking prices reached roughly 3,600-3,818 euros per square metre by 2026, up around 6% year-on-year and the highest in years, while gross yields range from about 3% in the priciest pockets to above 7% in higher-yield neighbourhoods. Bologna is forecast among Italy's fastest-growing markets for 2026, with university districts expected to see the strongest rent growth. As a Eurozone city it offers legal and currency stability, but investors should weigh real headwinds: Italy's lengthy purchase and bureaucratic processes, rising prices that compress yields at the top end, and growing regulatory attention to short-term rentals in the historic centre.
Florence City Guide
Italy
Florence is the cradle of the Italian Renaissance — Tuscany's regional capital, a UNESCO World Heritage City since 1982, and the city where Michelangelo's David, Botticelli's Birth of Venus, the Duomo, the Uffizi, and the Ponte Vecchio define an unrivalled concentration of cultural heritage. The city centre fits within a compact UNESCO buffer zone, with Centro Storico, Oltrarno (across the Arno), and the surrounding hills (San Miniato, Fiesole) anchoring the residential market. Population is 362,353 (city) / 714,000 (metro). Florence reached €4,737/m² in April 2026 (+5.43% YoY), with Centro Storico at €5,300/m² and Oltrarno/Historic Centre reaching €5,500-€6,000/m². Outer residential areas like Rifredi or Isolotto are €3,700-€3,900/m². Florence delivers Italy's strongest yield + heritage combination — gross rental yields ran 5.23-7.7% in Q3 2025 with city average 6.24%.
Milan City Guide
Italy
Milan is Italy's financial capital, fashion-and-design world centre, and the country's most expensive property market. Population is 1,362,863 (city) / 3,167,000 (metro). The city is anchored by the Duomo and the historic Centro Storico, the global luxury retail of the Quadrilatero d'Oro (Via Montenapoleone, Via della Spiga, Via Sant'Andrea), the art-and-design Brera district, and three landmark modern developments: Porta Nuova (Piazza Gae Aulenti and the Bosco Verticale vertical-forest skyscraper), CityLife (Hadid/Isozaki/Libeskind 'Three Towers' on the former Fiera grounds), and Garibaldi-Isola. Average property prices reached €5,188/m² in 2025 — the highest in Italy and roughly 50% above Rome's €3,759/m². Premium districts (Brera, Porta Nuova, CityLife) command €10,000+/m². Rental yields average 5.32% across the city. Milan captures a disproportionate share of Italy's HNW relocators using the renewed 2026 €300K Lump-Sum Tax regime.
Naples City Guide
Italy
Naples is Italy's third-largest city and the cultural capital of Southern Italy — anchored by Mount Vesuvius, the Bay of Naples, Pompeii + Herculaneum, the UNESCO-listed historic centre (Italy's largest at 1,700 hectares), and the world's most celebrated pizza tradition. The city has emerged from decades of post-war stagnation into Italy's most-watched emerging real estate market: prices rose +8.5% YoY in April 2026 to €2,684/m² average, with Posillipo (prestige sea-view residential) at €5,345/m² and gentrifying areas like Barra/Ponticelli at €1,501/m². Gross rental yields are among Europe's highest — 7.27% city average with neighborhoods reaching 12.92% for value 1-bedroom apartments. Naples is increasingly attracting international remote workers, lifestyle buyers, and yield investors drawn by Italy's 2026 €300K Lump-Sum Tax and the city's value-pricing relative to Rome or Milan.
Rome City Guide
Italy
Rome is the eternal city — 2,800 years of continuous habitation layered into a single urban fabric, from Imperial-era forums and Renaissance churches to fascist-era boulevards and post-war modernism. The city is divided into 22 historic rioni and 15 modern quartieri, each with distinct character and pricing. Centro Storico — the UNESCO-listed historic core — commands roughly €8,484/m² and the highest international-buyer share. Trastevere, Monti, Prati, and Testaccio anchor the next pricing tier. Across the city, average residential prices reached €3,759/m² in early 2026 (+6% YoY per Investropa), with gross rental yields ranging 3-8% depending on neighbourhood. Italy's national-level Imposta di Registro structure (2% prima casa or 9% non-prima-casa transfer tax) and the renewed 2026 €300K Lump-Sum Tax regime for HNW relocators support continued international buyer demand.
Venice City Guide
Italy
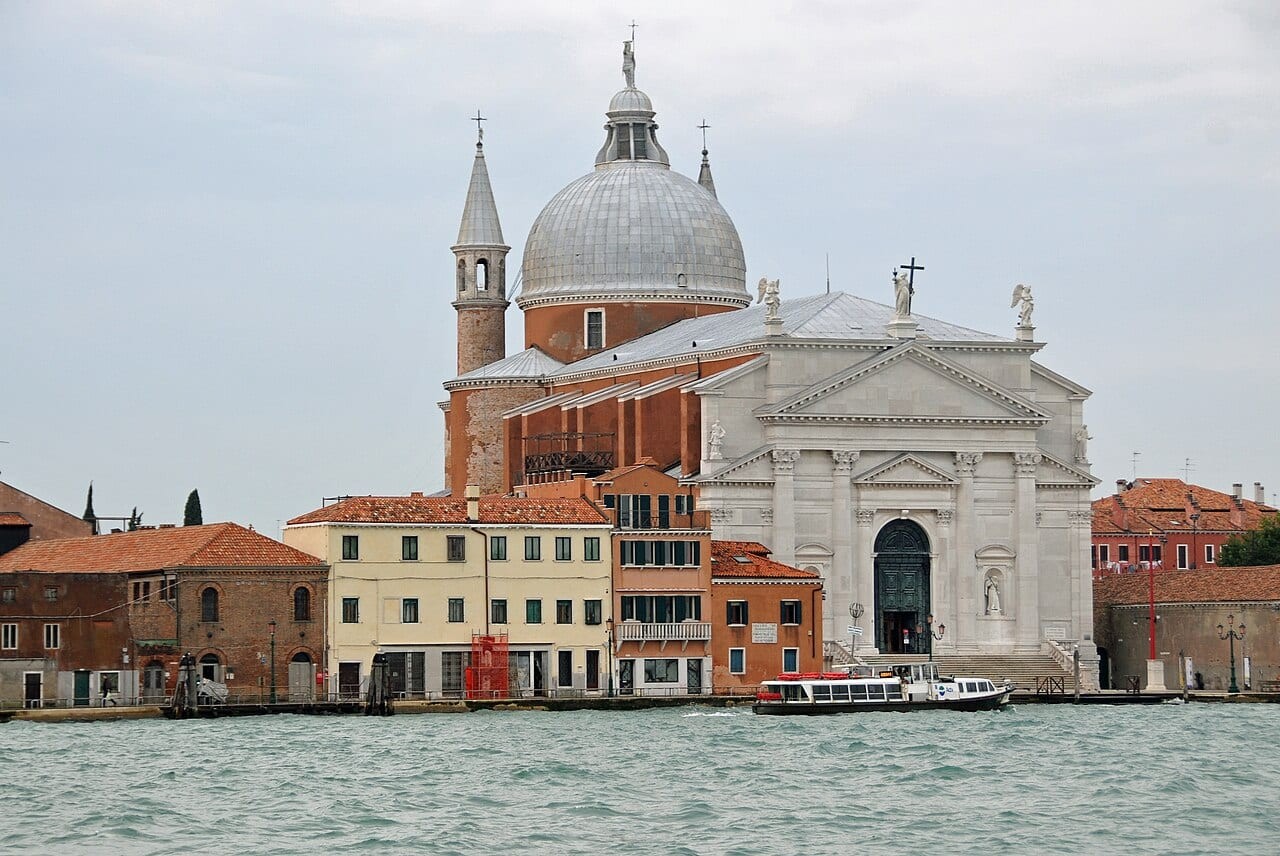
Venice is a property market like no other: a UNESCO-listed lagoon city of around 249,000 residents (less than 50,000 in the historic island core) where the near-total absence of new construction creates a structurally scarce supply of housing. That scarcity, combined with relentless global tourism and second-home demand, drives prices in the historic centre well above the Italian average: San Marco apartments range from 5,800 to 7,200 euros per square metre, while the citywide average reached roughly 4,800-4,900 euros/m2 in late 2025, up around 5% year-on-year. The market is sharply two-tiered: trophy lagoon apartments deliver modest long-let yields of 3.5-4.3% (Cannaregio near the Ghetto) but exceptional scarcity value, while the mainland districts of Mestre and Marghera offer entry prices as low as 1,400-2,000 euros/m2 and the strongest gross yields, around 4.5-5.5%, anchored by commuters, students and service workers. Tenant demand spans students, hospital and tourism staff, and a growing cohort of remote workers and expats. As a Eurozone city Venice offers currency and legal stability, but the risks are unusually specific: flood (acqua alta) exposure and the cost of maintaining historic island buildings, tightening short-term-rental and tourism regulation (including the day-tripper access fee), a shrinking resident population, and a flat-to-modest 12-month price outlook of roughly minus 3% to plus 5% for the historic centre.

Kingston City Guide
Jamaica
Kingston, the capital and the Caribbean's largest English-speaking city, is Jamaica's economic, financial and cultural engine, and the country's strongest income-yield market. Unlike the resort coasts, demand here is driven by professionals, diplomats, corporates and a deep long-let tenant pool, producing some of the highest urban rental yields in the region: Numbeo data shows gross yields of roughly 8.2% in the city centre and 6.6% outside it. Buy-side pricing runs from about US$170,000-$300,000 for entry condos and apartments, US$350,000-$700,000 for mid-range gated units, and US$1.5 million+ for luxury homes in the uptown hills. Prime uptown product (New Kingston, Norbrook, Cherry Gardens) trades around US$200-$350 per square foot. National rents accelerated 7.3% year-on-year in mid-2025, and uptown values have appreciated roughly 5-7% annually. Foreigners may buy freehold with no permit or nationality restriction, treated almost as locals; the only material limit is a 49% foreign-shareholding cap on company-held land. Transactions carry a 2% transfer tax, shared stamp duty and legal fees of 1.5-3%, with the BOJ policy rate eased to 5.75% improving financing conditions.
Montego Bay City Guide
Jamaica
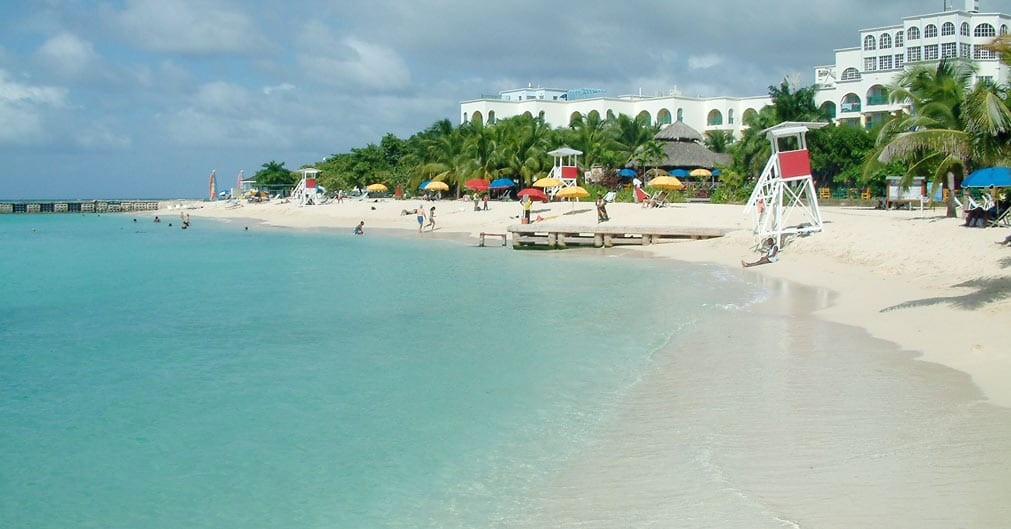
Montego Bay is Jamaica's premier resort city and the deepest, most liquid market for foreign property investors, anchored by Sangster International Airport (the Caribbean's busiest by some measures) and a tourism economy that drew a record 4.3 million visitors nationally in 2024 worth roughly US$4.35 billion. The market spans resort condos in Ironshore and Reading, golf and gated luxury at Rose Hall, and the Hip Strip / Doctor's Cave Beach core. Entry-level beach condos run from about US$180,000-$300,000, while gated and golf-community villas at Rose Hall reach US$700,000-$2.5 million+; quality coastal product trades around US$300-$450 per square foot. Short-let demand is strong, supporting gross rental yields of roughly 6-8% on well-located vacation units, with peak-season occupancy frequently above 75%. Foreigners may buy freehold property outright with no nationality restriction or special permit, treated almost identically to locals; only company-held land triggers a 49% foreign-shareholding cap. Buyers budget for 2% transfer tax (seller-side), shared stamp duty (currently flat for land conveyances) and typical legal fees of 1.5-3%. With national rents climbing 7.3% year-on-year in mid-2025 and the BOJ policy rate eased to 5.75%, MoBay remains the country's most investable destination.
Negril City Guide
Jamaica
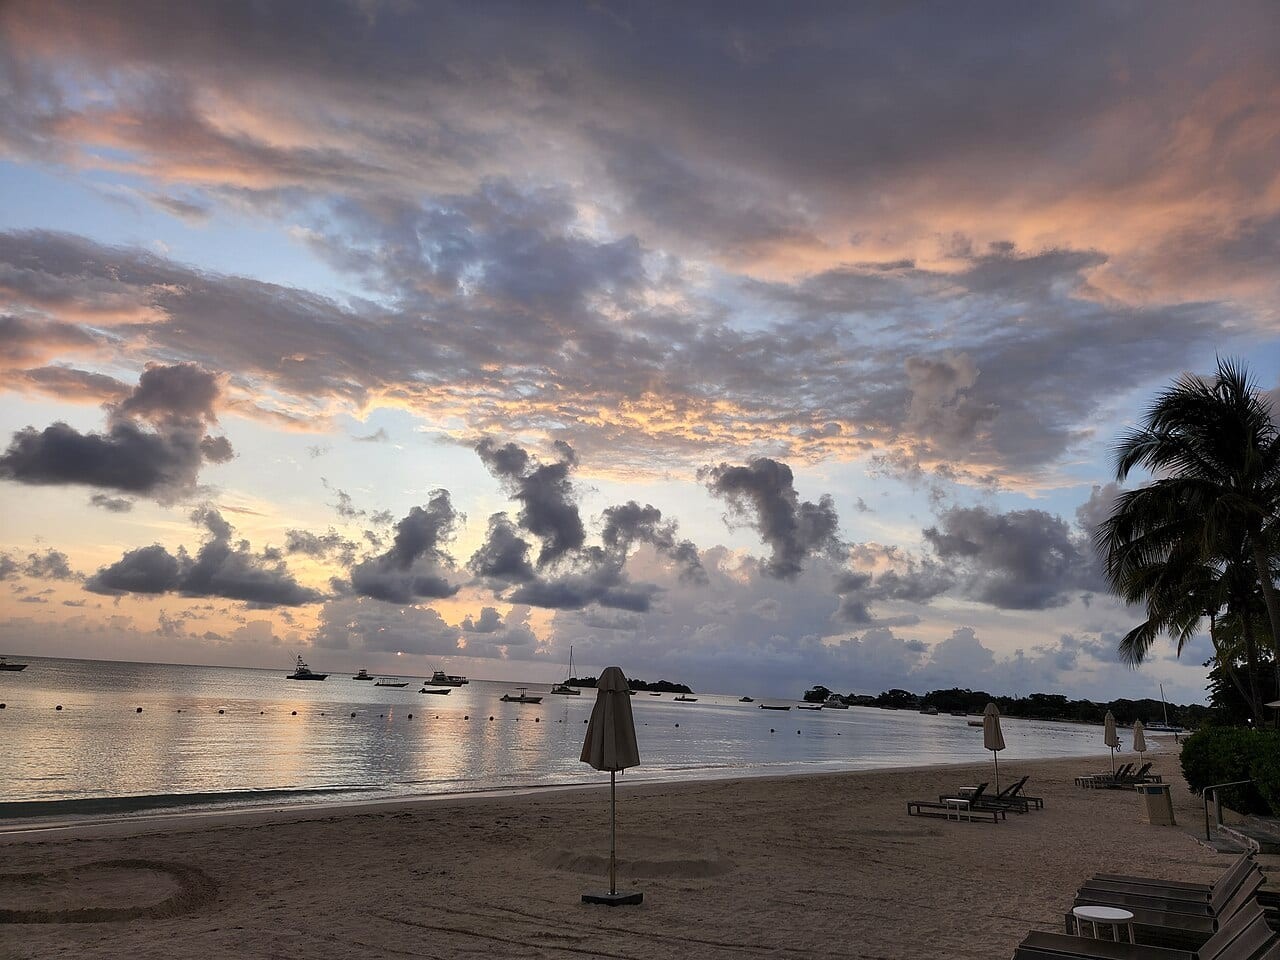
Negril, at Jamaica's western tip across Westmoreland and Hanover, is the island's most iconic beach destination, renowned for the white sands of Seven Mile Beach and the dramatic limestone cliffs of the West End. Its laid-back, eco-leaning tourism economy makes it a premier vacation-rental and boutique-resort market for foreign investors. Property runs from about US$170,000-$350,000 for condos and cottages, US$350,000-$900,000 for beach and cliff villas, and US$1 million+ for premium oceanfront estates and small resorts; quality coastal product trades around US$250-$420 per square foot. Short-let demand near Seven Mile Beach is strong, supporting gross yields of roughly 6-9% on well-managed units with high peak-season occupancy. Prices have appreciated about 5-6% annually. Foreigners may buy freehold with no nationality restriction or permit, treated nearly as locals; only company-held land carries a 49% foreign-shareholding cap. Buyers budget for 2% transfer tax (seller-side), shared stamp duty and legal fees of 1.5-3%. With national tourism at record levels and the BOJ rate eased to 5.75%, Negril remains a top lifestyle-and-yield destination.
Ocho Rios City Guide
Jamaica
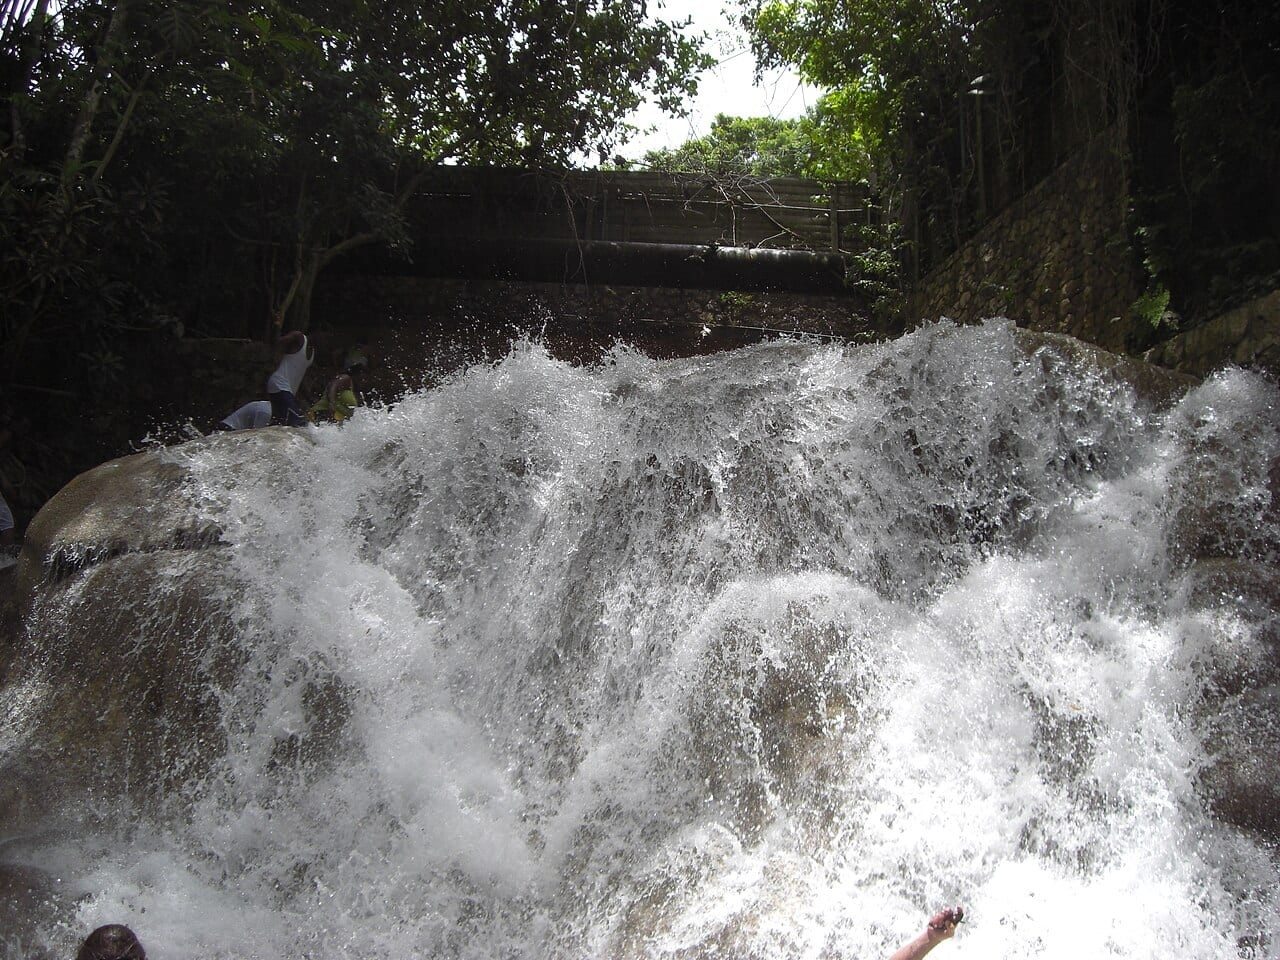
Ocho Rios, on Jamaica's north coast in Saint Ann, is a cruise-port and resort town built around natural attractions like Dunn's River Falls, making it a leading vacation-rental and second-home market. As a major cruise terminal and excursion hub, it sustains heavy seasonal visitor flow that underpins short-let demand for condos and villas. Property runs from about US$170,000-$300,000 for condos and townhouses, US$300,000-$700,000 for gated villas, and US$1 million+ for premium oceanfront estates; quality coastal product trades around US$250-$400 per square foot. Gross rental yields of roughly 6-8% are achievable on well-managed short-let units given strong peak-season occupancy, and prices have appreciated about 5-6% annually. Foreigners may buy freehold with no nationality restriction or permit, treated nearly as locals; only company-held land carries a 49% foreign-shareholding cap. Buyers budget for 2% transfer tax (seller-side), shared stamp duty and legal fees of 1.5-3%. With national tourism at record levels (4.3M arrivals, US$4.35B earnings in 2024) and the BOJ rate eased to 5.75%, Ocho Rios remains a core north-coast investment destination.

Amman
Jordan
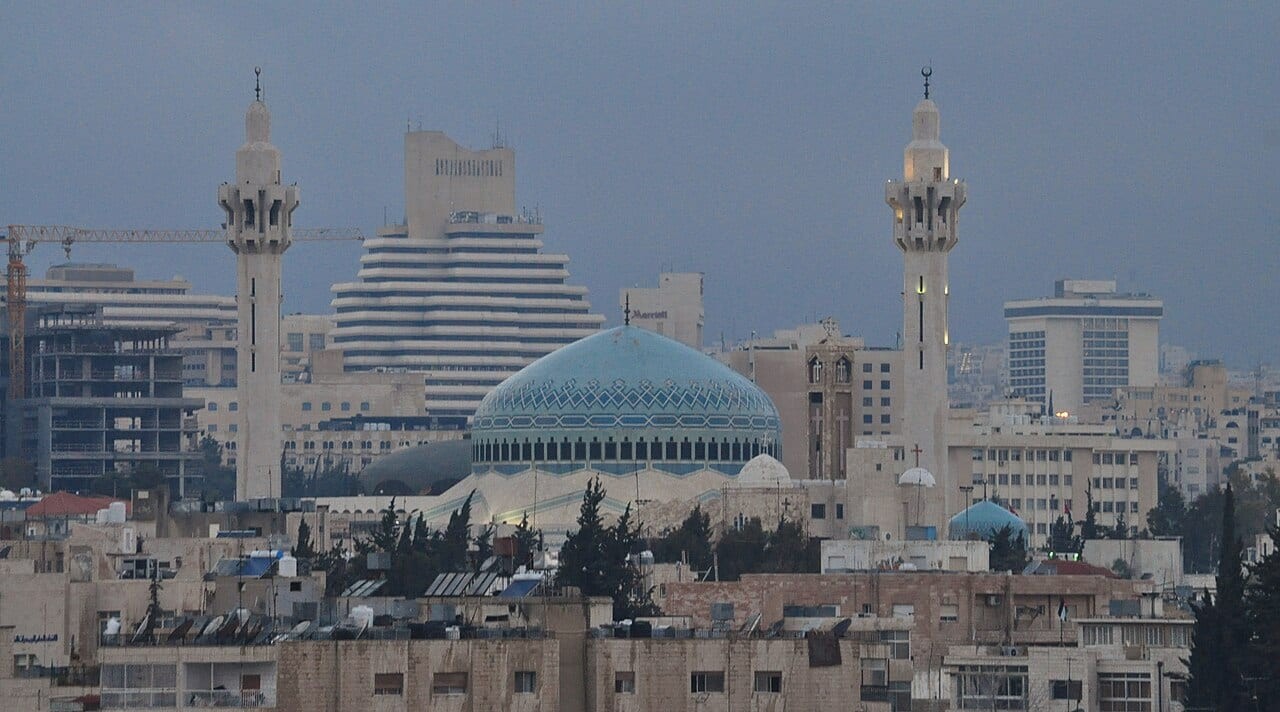
Amman is Jordan's capital and the country's economic, political, and cultural centre. Built across seven hills (now expanded across 19), the city has long been a regional safe harbour for capital and talent fleeing instability elsewhere in the Levant -- giving Amman a uniquely cosmopolitan, professional character. Residential prices in upscale districts (Abdoun, Sweifieh, Dabouq, 5th Circle area) range from JOD 800-1,800 per square metre (USD 1,130-2,540), with gross yields of 5.5-7.5%. Foreign nationals can purchase freehold property in Jordan with Council of Ministers approval (a routine process for non-restricted areas). GCC nationals enjoy simplified procedures. The market is USD-stable thanks to JOD's peg to the dollar at 0.708 since 1995. For international buyers, Amman offers a calm, family-oriented Levantine capital with USD-pegged currency, professional services in English, strong rental demand from regional NGO/diplomatic communities and university students, and reasonable yields. The catch: economic growth has been slow (2-3% GDP), labour markets are weak, and the broader regional security context adds risk premium.
Aqaba City Guide
Jordan
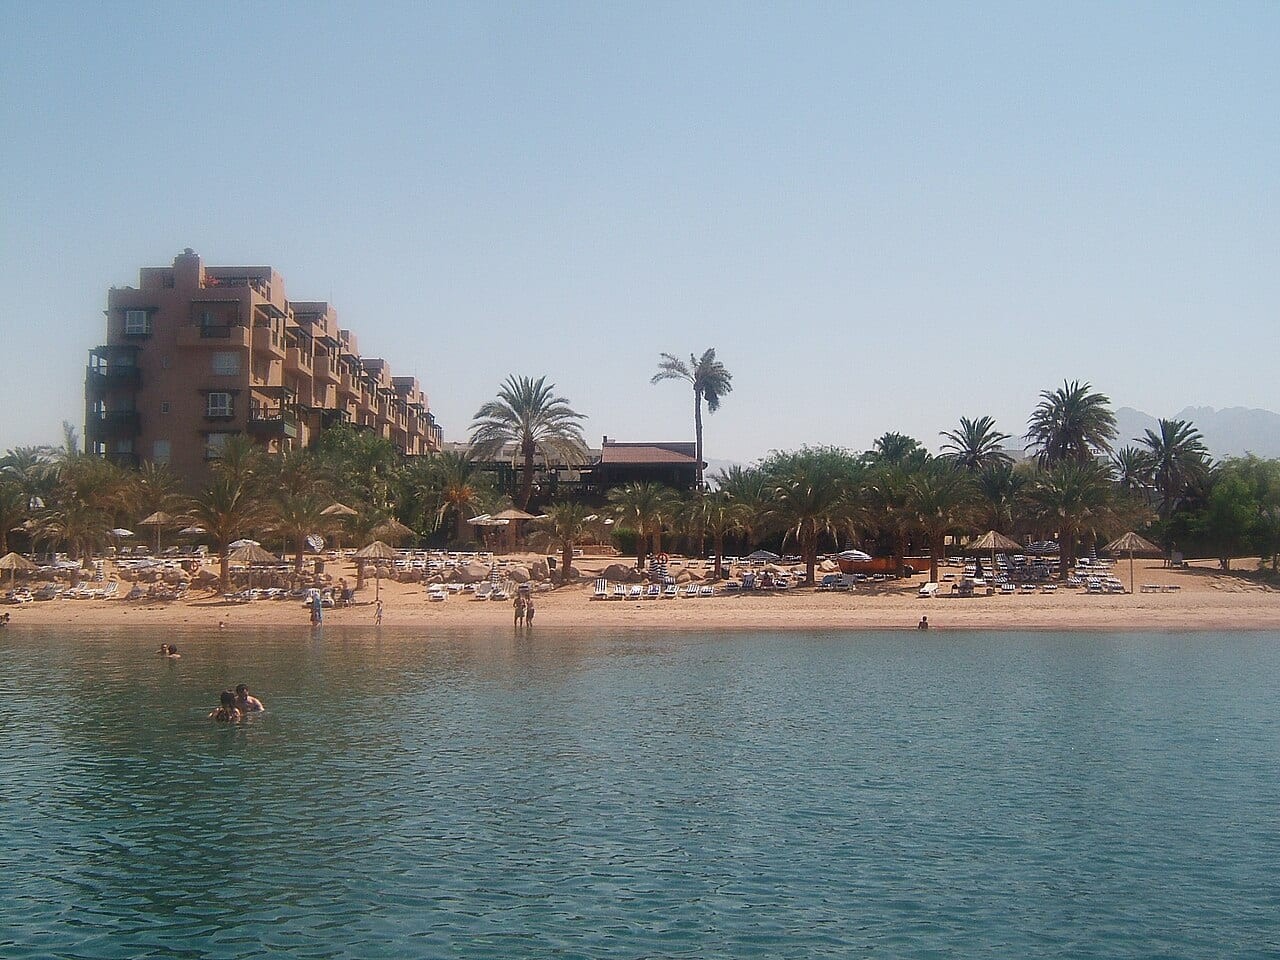
Jordan's only coastal city, Aqaba sits at the head of the Red Sea where the Aqaba Special Economic Zone (ASEZ), established in 2001 across 375 square kilometres with 27 kilometres of shoreline, gives investors a distinctly liberal regime: a flat 5% income tax, simplified customs, and a foreign-ownership framework friendlier than mainland Jordan. The waterfront is being reshaped by a cluster of mega-resorts: Ayla Oasis (1.4 billion USD, with a Greg Norman golf course), Saraya Aqaba (1.5 billion USD), the established Tala Bay community to the south, and the 10 billion USD Marsa Zayed regeneration of the old port that broke ground in 2024. Tourism is the core demand driver: hotel-managed and serviced apartments command the strongest occupancy and ROI, particularly waterfront stock in Tala Bay and Ayla. National property trading rose roughly 2% over the first nine months of 2025, and February 2025 reforms eased residency rules for foreign owners. With a population near 242,000 and steady infrastructure investment, Aqaba enters 2026 as Jordan's principal lifestyle and second-home market rather than a high-yield speculative play.
Irbid City Guide
Jordan
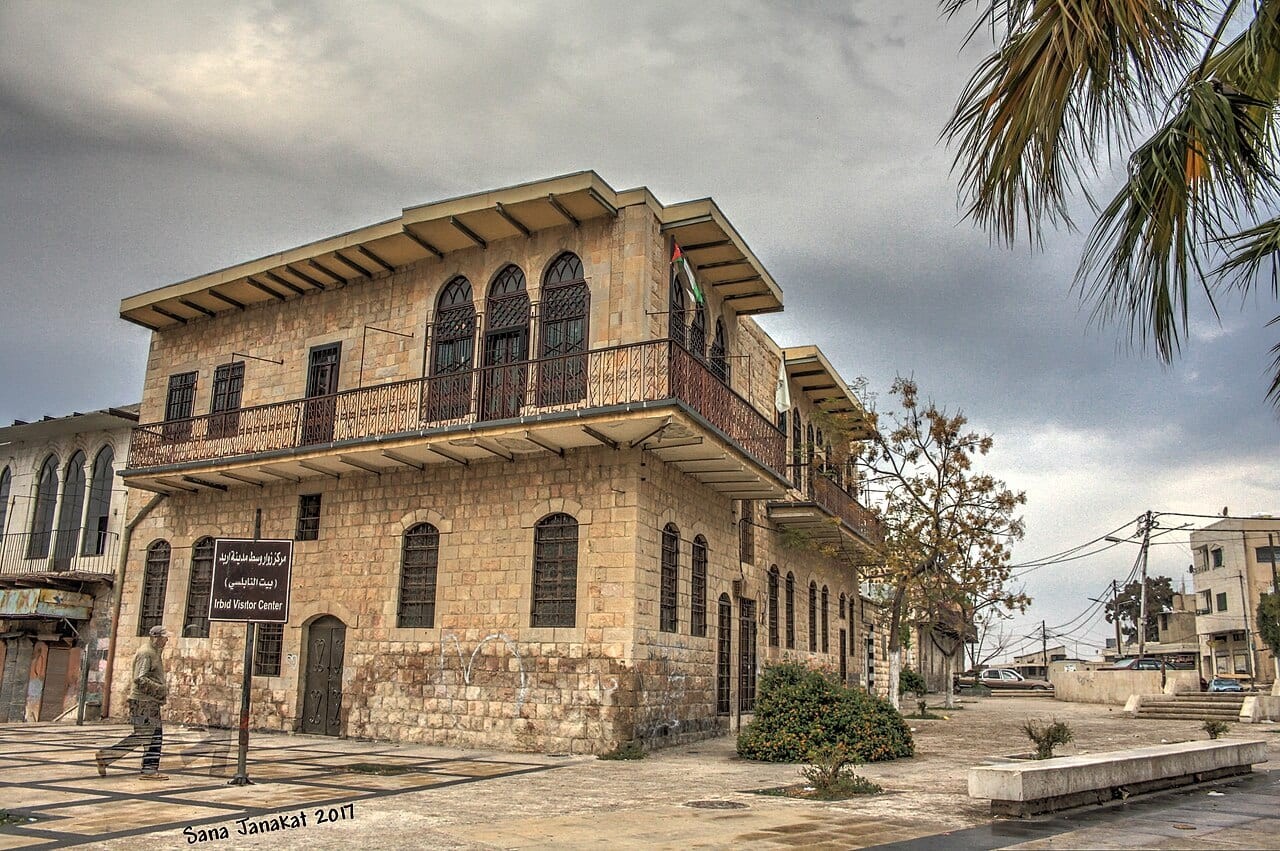
Irbid is Jordan's second- or third-largest city and the commercial hub of the fertile northern governorate, best known for Yarmouk University and the Jordan University of Science and Technology, which together make it the country's densest student city. Property is considerably cheaper than Amman, and a large, renewing student tenant base supports steady rental demand with gross yields typically in the 4-7% range. Foreign buyers face a meaningful legal gate: under Law 47/2006, non-Jordanians (non-Arabs in particular) need Council of Ministers approval and must satisfy a reciprocity test with their home country, and there is generally a five-year holding period before resale. This makes Irbid a stable, income-oriented market for patient investors rather than a quick-flip destination.

Almaty City Guide
Kazakhstan
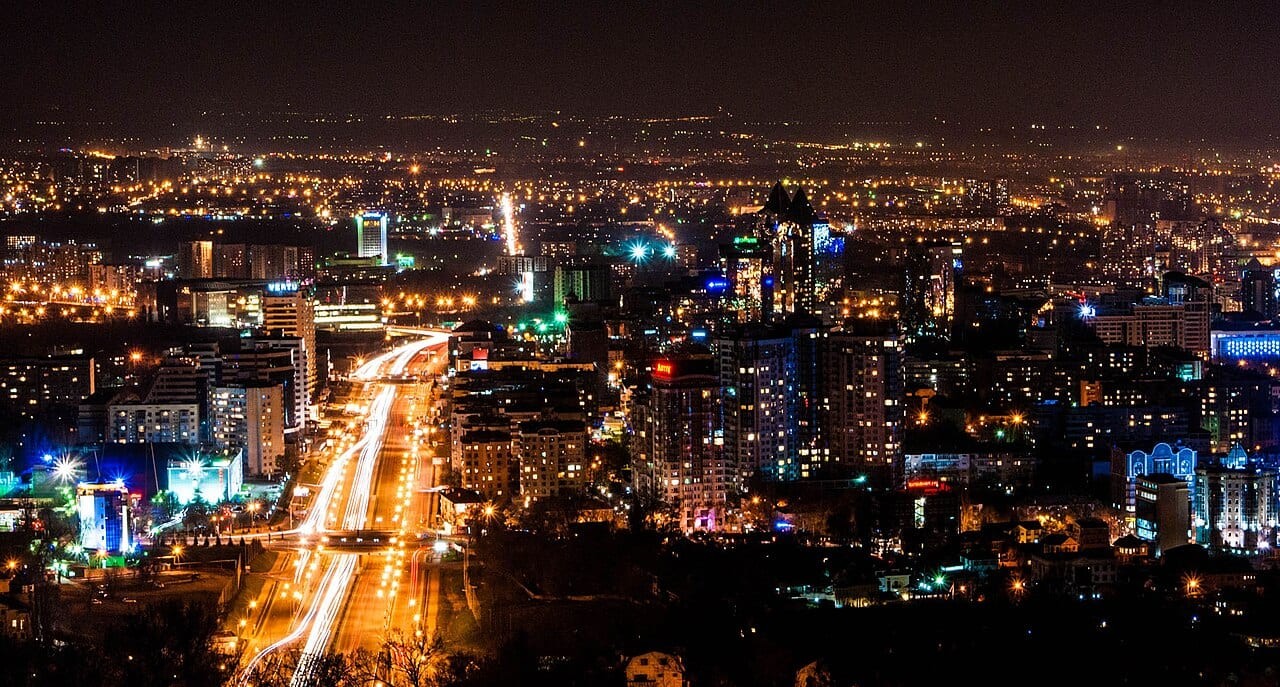
Almaty is Kazakhstan's commercial and financial capital and the deepest, most liquid property market in Central Asia. Though Astana took over as the political capital in 1997, Almaty still generates close to a quarter of national GDP, with a GDP per capita roughly a third higher than the new capital, and it hosts the country's largest concentration of banks, corporates, universities, and cultural institutions. Set against the Tien Shan mountains, the city of around 2.35 million residents combines a tree-lined Soviet-era core with new comfort- and business-class developments in southern districts such as Bostandyk and Medeu. Average residential values sit near USD 1,400 per square metre in late 2025, economy-class one-bedroom apartments trade around USD 50,000-55,000, while strong tenant demand keeps gross rental yields among the highest of any major regional city, broadly in the 7-9% range. Prices rose more than 4% in the opening months of 2026 and annual rents climbed close to 12% through 2025. For international buyers, Almaty offers Eurasian-gateway connectivity, a maturing mortgage market, and entry prices a fraction of comparable Eastern European capitals, balanced against tenge currency exposure and seismic considerations.